
Updated Kamoa-Kakula life-of-mine plan to be released in March 2027, detailing the route to restoring Kamoa-Kakula Copper Complex to the very top tier of global producers
■
Refreshed operating plan will deliver a flexible and derisked operation, introducing shallow, high-grade open-pit mining at Kamoa to complement the underground mines
■
Short-term 2027 Kamoa-Kakula copper production guidance revised to 300,000 to 350,000 tonnes of copper at a cash cost (C1) of $2.50/lb. to $3.00/lb.
■
All full capacity, the existing Phase 1, 2 and 3 concentrators target 400,000 to 450,000 tonnes of copper production
■
Kamoa-Kakula to increase steady-state copper production to ~500,000 tonnes per annum with Phase 4 milling expansion; utilizing pre-built foundations and Phase 3 mill design
■
Western Forelands' 2027 in-fill drilling and engineering program to bring additional copper production from wholly-owned, shallow, high-grade open-pit mines
■
60-MW hybrid solar facilities fully operational, significantly reducing power and diesel costs; expanding to 120 MW by Q1 2028
■
Sulphuric acid production averaging ~1,250 tonnes per day; contract prices averaging over $900 per tonne
■
Kipushi on track for another record-breaking year
■
Platreef’s Phase 2 concentrator on schedule for completion in Q4 2027, inaugurating our world-leading producer of platinum, palladium, nickel, rhodium, gold, and copper
■
Ivanhoe Mines reports Q3 2026 profit of $45M and Adjusted EBITDA of $241M, including $190M of attributable EBITDA from Kamoa-Kakula and $108M EBITDA from Kipushi
■
Kamoa-Kakula recognized record quarterly revenue of
over $1 billion
Johannesburg, South Africa--(Newsfile Corp. - November 3, 2026) - Ivanhoe Mines' (TSX: IVN) (OTCQX: IVPAF) President and Chief Executive Officer, Marna Cloete, and Chief Financial Officer, David van Heerden, today announced the company's financial results for the third quarter of 2026, as well as an operations and project development update.
Ivanhoe Mines is a leading Canadian mining company with three principal tier-one mining operations in Southern Africa: the Kamoa-Kakula Copper Complex in the Democratic Republic of the Congo (DRC); the ultra-high-grade Kipushi zinc-copper-lead-germanium mine, also in the DRC; and the Platreef platinum, palladium, nickel, rhodium, gold, and copper mine in South Africa.
In addition, Ivanhoe Mines is expanding the Makoko District copper discovery in the Western Forelands, in the DRC, as well as exploring for new sedimentary-hosted copper discoveries across its vast and highly prospective exploration licence packages in the DRC, Angola, Zambia, and Kazakhstan.
All figures are in U.S. dollars unless otherwise stated.
Founder and Co-Chairman Robert Friedland commented:
"Our engineering teams have made the necessary decisions at Kamoa-Kakula to derisk and restore one of the world's greatest copper complexes to the top of tier-one status. The revised production and cost guidance over the short term reflects a disciplined approach to the ongoing turnaround at Kamoa-Kakula, prioritizing operational stability, mining flexibility and the sustainable recovery of annualized copper production to approximately 500,000 tonnes.
"Operational improvements that we've already made are delivering strong tangible results… Mining rates increased significantly during the quarter, concentrator recoveries continue to improve, and our copper smelter is generating substantial economic benefits… Sales from sulphuric acid are now more than paying for our smelter's operating costs… We continue to benefit from the substantially lower transportation costs of delivering our copper to the world market in 99.7%-pure copper anodes… Our phased investment in solar power is already displacing very expensive diesel-powered generation. These structural improvements will strengthen Kamoa-Kakula's competitiveness long after our current challenges have been overcome.
"We have updated our pathway at Kamoa-Kakula to restore annual copper production to approximately 500,000 tonnes through the Phase 4 expansion, while the introduction of very high-grade open-pit mining will create resilience and operational flexibility across the entire complex. Kamoa-Kakula will unveil this next chapter of development in March 2027.
“Meanwhile, Kipushi has grown to be the world’s third-largest zinc mine, demonstrating the unique quality of the highest-grade zinc orebody in the world… delivering record zinc production and more than doubling quarterly EBITDA to $108 million… At Platreef, we continue to build one of the world's most important producers of platinum, palladium, nickel, rhodium, gold, and copper… and immediately to the west of Kamoa-Kakula, our exploration team continues to unlock and prove the immense potential of the Western Forelands, home to the world's largest, fastest-growing and highest-grade copper discovery of the past decade.
"The world is entering an era of unprecedented demand for the metals that underpin electrification, reduction of global warming gases, artificial intelligence, advanced manufacturing and national security. The importance of discovering, developing and responsibly producing these metals has never been greater. Ivanhoe's team is more intensely dedicated than ever to the task."
FINANCIAL HIGHLIGHTS
- Ivanhoe Mines recorded a profit after tax of $45 million for Q3 2026, compared to $31 million for the same period in 2025 and a profit of $46 million for Q2 2026. The quarterly profit was attributable to the segmental profit from the Kipushi Mine of $47 million and the company's share of profit from the Kamoa-Kakula joint venture of $25 million, partly offset by increased exploration expenditure.
- Ivanhoe Mines' Q3 2026 Adjusted EBITDA was $241 million, compared to $86 million for the same period in 2025 and $179 million for Q2 2026, which includes an attributable share of EBITDA from Kamoa-Kakula of $190 million for Q3 2026, compared with $76 million for the same period in 2025.
Kamoa-Kakula sold 67,025 tonnes of copper (net of payability) during the third quarter at an average realized copper price of $6.12/lb., the majority of which were realized earlier in the quarter, when copper prices were lower.
The relatively low average realized copper price of $6.12/lb. for the third quarter was due to a high proportion of third quarter copper sales, totaling 61,958 tonnes of payable copper, that was sold but remained provisionally priced at the end of Q3. This balance was remeasured to the quarter-end closing copper price of $6.55/lb., which is the reason for the majority of the $20.8 million positive remeasurement to revenue in the third quarter.
At the end of the third quarter, there were approximately 43,000 tonnes of unsold copper in inventory.
- Kamoa-Kakula recognized record revenue of $1,034 million, an operating profit of $288 million and EBITDA of $478 million for the quarter, equivalent to an EBITDA margin of 46%. This compares to recognized revenue of $880 million, an operating profit of $160 million and EBITDA of $385 million for the second quarter, equivalent to an EBITDA margin of 44%.
- Kamoa-Kakula's cost of sales per pound of payable copper sold was $4.59/lb. for the third quarter, compared with $4.86/lb. in Q2 2026.
- Despite elevated diesel prices, full-year cash costs (C1) are on target to achieve 2026 guidance range from $2.60/lb. to $3.00/lb. Kamoa-Kakula's cash cost (C1) per pound of payable copper produced averaged $3.00/lb. for Q3 2026. Cash cost (C1) for the first nine months of 2026 averaged $2.80/lb., at the mid-point of the full-year guidance range.
- Ivanhoe Mines revises 2027 Kamoa-Kakula cash cost guidance range to $2.50 - $3.00 per pound (previously $2.10 - $2.50 per pound) as a result of prolonged, elevated diesel prices, lower grades and lower production for 2027. Cash costs are expected to trend lower than $2.50 per pound prior to the Phase 4 expansion.
- Kamoa-Kakula's Q3 2026 smelter operating costs averaged $0.51/lb., which were more than offset by $0.69/lb. in sulphuric acid by-product credits. In addition, logistics charges in Q3 2026 of $0.29/lb. were less than half of the equivalent cost prior to the commencement of smelter operations, due to the export of 99.7%-pure copper anodes instead of exporting concentrate containing 35% to 40% copper.
- Kamoa-Kakula sold 109,424 tonnes of high-strength sulphuric acid during the quarter, at an average price of $915 per tonne. Sulphuric acid prices are expected to remain elevated for the foreseeable future, with 3-month contracts from November expected to average approximately $900 per tonne.
- Kamoa-Kakula's capital expenditure in Q3 2026 was $206 million. Capital expenditure for the nine months ended September 30, 2026, was $797 million. 2026 capital expenditure guidance has been updated by lowering the upper end of the range by $200 million to $1,100 million - $1,200 million (previously $1,100 million - $1,400 million). The $200 million underspend has been deferred to 2027, where the full-year capital expenditure guidance range has been increased to $950 million - 1,150 million (previously $750 million - $950 million). This estimate excludes capitalized pre-stripping for open pits estimated to be $100 million to $200 million.
- Kipushi sold a record 69,384 tonnes of zinc (net of payability) during the quarter, at an average realized zinc price of $1.73/lb., compared with 43,424 tonnes in Q2 2026 at an average realized zinc price of $1.58/lb. Unsold zinc in concentrate held in inventory decreased by approximately 2,000 tonnes from the end of Q2 2026, but was still approximately 12,000 tonnes more than at the end of Q1 2026.
- Kipushi recognized a quarterly revenue of $255 million, a segmented profit of $47 million and EBITDA of $108 million in Q3 2026, which is equivalent to an EBITDA margin of 43%. This compares with EBITDA of $51 million and EBITDA margin of 35% in Q2 2026.
- Kipushi's cost of sales per pound of payable zinc sold was $1.14/lb. for the third quarter and was $1.06/lb. in Q2 2026. Cash cost (C1) per pound of payable zinc sold in the third quarter averaged $0.91/lb. and year-to-date averaged $0.89/lb. Kipushi is on track to achieve the full-year cash cost (C1) guidance of $0.85/lb. to $0.95/lb.
- Platreef's capital expenditure during Q3 2026 was $124 million. The full-year guidance range has been increased to $415 million - $445 million (previously $350 million - $380 million) to account for additional capitalized costs related to Phase 1 operations prior to commercial production.
- Ivanhoe Mines has a strong treasury position with cash and cash equivalents on hand of $643 million as at September 30, 2026.
OPERATIONAL HIGHLIGHTS
- In Q3 2026, Kamoa-Kakula produced 76,401 tonnes of copper in saleable products. 61,506 tonnes of anode and 5,645 tonnes of copper in slag concentrate were produced by Kamoa-Kakula's copper smelter, 2,347 tonnes of copper in blister were produced by the Lualaba Copper Smelter (LCS) in Kolwezi and 6,904 tonnes of copper fines were designated for sale. In Q2 2026, Kamoa-Kakula produced 64,328 tonnes of copper contained in anode, blister and slag concentrate held for sale, of which 62,072 tonnes of anode and 2,256 tonnes of copper in blister.
- Kamoa-Kakula 2026 production is expected to be approximately 290,000 tonnes of copper in saleable products.
- Work on the updated life-of-mine plan is advancing well and is on track to be released in March 2027, building on the key recommendations from the 2026 Kamoa-Kakula Mineral Resource Estimate (2026 Kamoa-Kakula MRE), which was released on March 31, 2026. Work completed to date includes updated geological, hydrological and geotechnical models for Kamoa and Kakula, supported by in-fill drilling and engineering trade-off studies.
- High-grade open-pit mining will be introduced in shallow areas of the Kamoa orebodies to provide greater mining flexibility and reduce operational risk. Pre-stripping of the first starter pits to commence in Q1 2027, with first ore expected in Q3 2027.
- 2027 production guidance lowered to 300,000 - 350,000 tonnes of copper. In addition, Kamoa-Kakula's steady-state capacity of the Phase 1, 2 & 3 concentrators is reduced to 400,000 - 450,000 tonnes of copper, prior to the Phase 4 expansion, due to prioritizing ore from open pits while the Kakula turnaround is underway.
- Detailed engineering design for the Phase 4 expansion, to increase production capacity to approximately 500,000 tonnes of copper, will commence in Q1 2027. Similar to prior concentrator expansions, Phase 4 shares certain civil infrastructure with Phase 3, and can be completed in a timeline of 18 to 24 months from project approval.
- Mining rates across the complex increased by 20% quarter-on-quarter to over 1.2 million tonnes per month, equivalent to approximately 14.4 million tonnes per annum, as tonnes mined from stoping increased by 84%.
- Kamoa-Kakula's on-site copper smelter, the largest in Africa, has been operating at approximately 1,250 tonnes per day, or 60% of capacity, since mid-February. The smelter produced a record 118,638 tonnes of high-strength sulphuric acid during the quarter.
- Kamoa-Kakula's on-site hybrid solar photovoltaic (PV) facility with battery energy storage system (BESS) fully ramped up by quarter end, delivering 60 MW of continuous baseload power to the complex. This is expected to reduce energy costs by $0.10/lb. to $0.20/lb. of payable copper produced, as Kakula dewatering is switched over from being powered by back-up diesel generators, to the new facility in mid-October.
- Kamoa-Kakula is advancing plans to double baseload power from the hybrid solar facilities to 120 MW by the end of Q1 2028. Two tenders, totaling 60 MW, were awarded, along with accompanying power purchase agreements (PPA) signed in Q2 and Q3. In addition, discussions are underway to expand the existing hybrid solar facilities by a further 30 MW, bringing total on-site planned capacity to 150 MW.
- Recoveries at the Phase 1 and 2 concentrators have improved at Kamoa-Kakula by approximately 5%, driven by the completion of Project 95 upgrades. Concentrator recoveries averaged 89% in Q3, with a record 92% achieved over two weeks in mid-October.
- At Kipushi, the concentrator milled 193,581 tonnes of ore at a record average grade of 41.6% zinc during the third quarter, producing a record 77,147 tonnes of zinc in concentrate. The concentrator milled 200,774 tonnes of ore at an average grade of 38.7% zinc during the second quarter, producing 70,177 tonnes of zinc in concentrate.
- Ivanhoe Mines tightens its 2026 production guidance for the Kipushi Mine to the upper end of the range of 270,000 to 290,000 (previously 240,000 to 290,000) tonnes of zinc in concentrate, which is expected to rank Kipushi as one of the world's top three largest zinc mines.
- The tender for Kipushi's hybrid solar PV project is expected to be awarded in the first quarter of 2027. The facility will be designed to provide 10 MW of continuous baseload power, providing approximately 50% of the site's energy needs. The facility is expected to be operational by mid-2028 and will significantly reduce diesel consumption from on-site backup generators.
- Since quarter-end, Kipushi's operations have been supported by an additional 10 MW of grid-supplied power from third-party providers. The additional power is expected to reduce power instability at Kipushi and reduce power costs from the back-up diesel generators.
- At Platreef, the Phase 1 concentrator milled 99,391 tonnes of ore during Q3 2026, at an average feed grade of 2.30 grams per tonne, producing 4,552 ounces of platinum, palladium, rhodium and gold (3PE +Au). Phase 1 operations continue to ramp up to commercial production, therefore, production rates achieved to date do not reflect steady-state conditions.
- The Phase 1 concentrator continued to be campaigned during the quarter, fed by lower-grade development ore. Identified bottlenecks in the underground materials handling and tailings filtration systems are largely resolved, with mining and milling rates expected to improve further in the fourth quarter. Milling is expected to progressively increase over the next few months, with the Phase 1 concentrator milling approximately 70% of design in October 2026.
- Earthworks on the Phase 2 expansion's 3.3-million-tonne-per-annum concentrator is nearing completion with civil works advancing. The concentrator is on schedule for completion by the end of 2027. Once fully ramped up, Phase 2 operations are expected to have a design capacity of over 450,000 ounces of platinum, palladium, rhodium, and gold (3PE + Au), plus approximately 9,000 tonnes of nickel and 6,000 tonnes of copper.
- The widening of Shaft #2 from its current diameter of 3.1 metres to 10 metres continued during the quarter. Shaft #2 is expected to be ready to hoist labour and materials by the end of 2028 and ore by the end of 2029.
- In the Western Forelands, an updated Mineral Resource estimate was announced on September 8, 2026, with Indicated Mineral Resources of 42 million tonnes at 2.66% copper, plus Inferred Mineral Resources of 612 million tonnes at 1.80% copper (100% basis). The updated Mineral Resource firmly ranks the Western Forelands as the world's largest and highest-grade copper discovery of the past decade.
- In the 15 months since the 2025 Mineral Resource update, approximately 64,000 metres of drilling have been completed across 106 holes, adding 0.13 million tonnes of contained copper in the Indicated Mineral Resource category, and 2.63 million tonnes of contained copper in the Inferred category.
- Western Forelands' 2026 exploration drill program of 94,500 metres, the largest ever, is on schedule to be completed by year-end. By the end of Q3, drilling was approximately 80% complete. The drill program is set to be upsized to 120,000 metres from Q4 2026, primarily focused on infill drilling of shallow mineralization with potential for open-pit extraction.
Conference call for investors on Wednesday, November 4, 2026
Ivanhoe Mines will hold an investor conference call to discuss the results on Wednesday, November 4, at 10:30 a.m. Eastern Time / 8:30 a.m. Pacific Time. The conference call will conclude with a question-and-answer (Q&A) session. Media are invited to attend on a listen-only basis.
To view the webcast, use the link:
https://meetings.lumiconnect.com/400-316-378-071
Audience phone numbers:
Local - Toronto +1 (416) 855-9085
Toll Free - North America +1 (800) 990-2777
Conference ID: 32677
An audio webcast recording of the conference call, together with supporting presentation slides, will be available on Ivanhoe Mines' website at www.ivanhoemines.com.
After issuance, the condensed consolidated interim financial statements and Management's Discussion and Analysis will be available at www.ivanhoemines.com and www.sedarplus.ca.
Read Ivanhoe's Third Quarter 2026 Sustainability Review:
Ivanhoe Mines' MSCI ESG rating was upgraded to AA this quarter, reflecting the company's management of material environmental, social and governance risks relative to industry peers.
https://www.ivanhoemines.com/investors/document-library/#sustainability
During Q3 2026, the group achieved a combined Lost Time Injury Frequency Rate (LTIFR) of 0.41 and a Total Recordable Injury Frequency Rate (TRIFR) of 1.98 per 1,000,000 hours worked. As previously disclosed, regrettably, one loss-of-life incident occurred underground at the Kakula Mine at the start of the quarter.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_bbd1221624ca7948_002full.jpg
A breakdown of Ivanhoe's health and safety performance is available in the Q3 2026 Sustainability Review.
In Memoriam: Ivano Manini
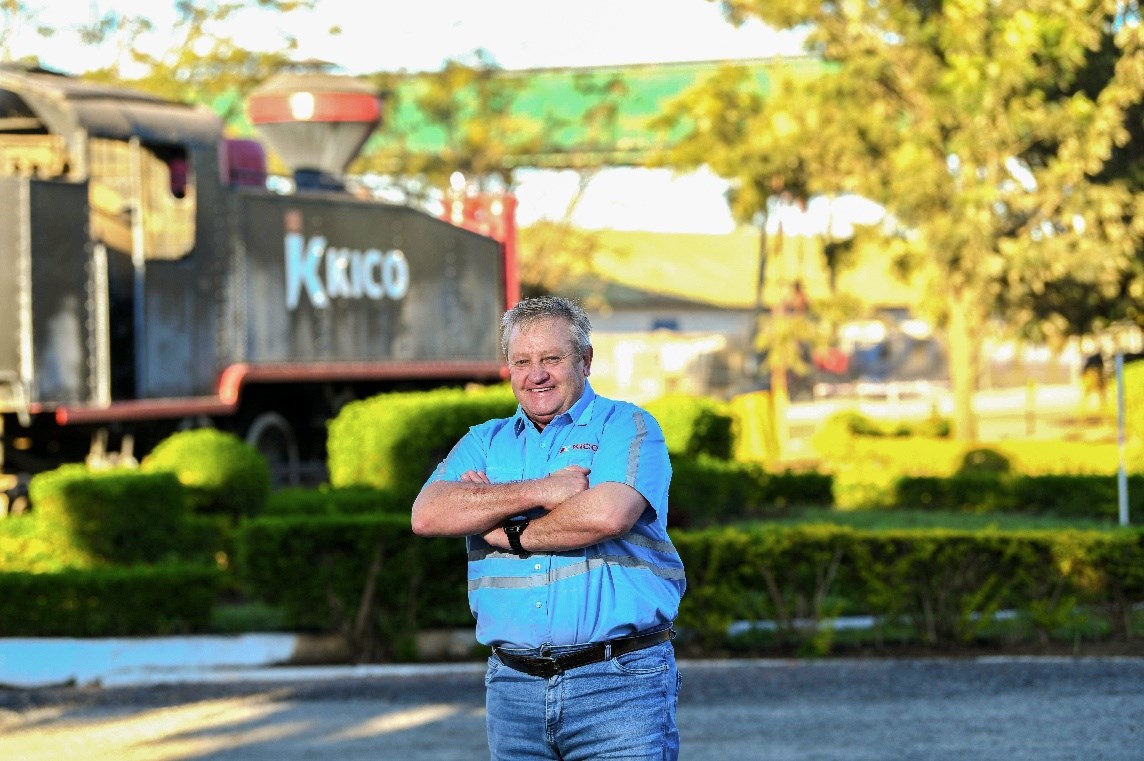
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_bbd1221624ca7948_003full.jpg
Ivanhoe Mines mourns the recent passing of Ivano Manini, General Manager of Kipushi Mine.
Mr. Manini was a valued member of the Ivanhoe family for the past 11 years and was an integral part of the Company's senior management team. Throughout his career with Ivanhoe, Mr. Manini held key positions at Kamoa-Kakula, Platreef and, most recently, at Kipushi. He played an instrumental role in Ivanhoe's success, most notably in the remarkable rebirth of the historic Kipushi Mine, which he oversaw from construction through to its record-breaking operations today.
Mr. Manini's leadership, dedication and commitment to Ivanhoe Mines and its people will leave a lasting legacy. He will be deeply missed by his colleagues and friends, and our thoughts and heartfelt condolences are with his family and loved ones.
Kipushi joint-venture partner Gécamines’ CEO, Baraka Kabemba, commented:
"Mr. Manini's leadership throughout the mine's redevelopment and transition into operations helped bring to life a project of great historical and economic significance for the Democratic Republic of the Congo.
On behalf of Gécamines, we extend our deepest condolences to his family, friends and colleagues at Ivanhoe Mines. His contribution to Kipushi and to our partnership will not be forgotten."
Principal projects and review of activities
1. Kamoa-Kakula Copper Complex
39.6%-owned by Ivanhoe Mines
Democratic Republic of the Congo
The Kamoa-Kakula Copper Complex is operated as the Kamoa Holding joint venture between Ivanhoe Mines and Zijin Mining. The complex covers a licence area of 400 square kilometres and is approximately 25 kilometres southwest of the town of Kolwezi on the far western edge of the Central African Copperbelt.
Kamoa Holding holds an 80% interest in Kamoa-Kakula, with the DRC government holding the remaining 20% interest. Ivanhoe and Zijin Mining, therefore, each hold an indirect 39.6% interest in Kamoa-Kakula, with Crystal River holding an indirect 0.8% interest. Kamoa-Kakula's full-time employee workforce is over 7,785, and over 90% are Congolese.
Copper production at Kamoa-Kakula commenced in May 2021 from the Phase 1 concentrator, which was delivered ahead-of-schedule. Two further concentrator expansions have since successfully been delivered ahead of schedule, and a 500,000-tonne-per-annum, direct-to-blister copper smelter. The smelter produced its first batch of 99.7%-pure copper anodes in late 2025. Kamoa-Kakula ranks among the largest and highest-grade copper complexes globally.
Kamoa-Kakula summary of operating and financial data
| Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | |
| Ore tonnes milled (000's tonnes) | 3,493 | 2,968 | 3,108 | 3,374(4) | 3,456 |
| Copper ore grade processed (%) | 2.22% | 2.39% | 2.32% | 2.35% | 2.47% |
| Copper recovery (%) | 87.6% | 87.4% | 85.6% | 85.7% | 82.7% |
| Copper in concentrate produced (tonnes) | 68,188 | 61,134 | 61,906 | 71,569 | 72,143 |
| Total contained copper in saleable products (tonnes)(1) | 76,401 | 64,328 | 71,417 | - | - |
| Payable copper sold (tonnes)(2) | 67,025 | 61,249 | 66,619 | 78,469 | 61,528 |
| Cost of sales per pound ($ per lb.) | 4.59 | 4.86 | 3.90 | 3.80 | 3.23 |
| Cash cost (C1) ($ per lb.)(3) | 3.00 | 2.84 | 2.58 | 2.99 | 2.62 |
| Realized copper price ($ per lb.) | 6.12 | 5.99 | 5.79 | 4.98 | 4.42 |
| Sales revenue before remeasurement ($'000) | 1,013,208 | 847,627 | 872,539 | 782,691 | 555,293 |
| Remeasurement of contract receivables ($'000) | 20,779 | 32,818 | (10,237) | 83,353 | 11,072 |
| Sales revenue after remeasurement ($'000) | 1,033,987 | 880,445 | 862,302 | 866,044 | 566,365 |
| EBITDA ($'000) | 478,216 | 384,887 | 397,476 | 331,121 | 195,597 |
| EBITDA margin (% of sales revenue) | 46% | 44% | 46% | 38% | 35% |
All figures in the above tables are on a 100%-project basis. Metal reported in concentrate is before refining losses or deductions associated with smelter terms. This release includes “EBITDA”, “Adjusted EBITDA”, “EBITDA margin”, “Pro-rata cash and cash equivalents” and "Cash cost (C1)", which are non-GAAP financial performance measures. For a detailed description of each of the non-GAAP financial performance measures used herein and a detailed reconciliation to the most directly comparable measure under IFRS Accounting Standards, please refer to the non-GAAP Financial Performance Measures and Pro-Rata Financial Ratios sections of the release and the company’s MD&A for the three and nine months ended September 30, 2026. Rounding errors may affect totals.
(1) From 2026, total contained copper in saleable products includes anodes produced by Kamoa-Kakula's on-site smelter, concentrate toll-treated into blister at the LCS smelter, as well as slag concentrate and high-grade fines produced by Kamoa-Kakula that are designated for sale to third parties as they are unable to be smelted on-site or at LCS. Prior to 2026, total contained copper consists of copper in concentrate by the Phase 1, 2 and 3 concentrators.
(2) Payable copper in concentrate sold is net of 96.7% payability. Payable copper in anode or blister sold is net of 99.7% payability.
(3) Units in U.S. dollars per payable pound of copper in saleable product produced.
(4) Ore tonnes milled in Q4 2025, excludes 160,000 tonnes of ore milled at the smelter's slag flotation plant.
Kamoa-Kakula cash cost (C1) breakdown:
| Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | ||
| Mining | ($ per lb.) | 1.66 | 1.46 | 1.39 | 1.22 | 1.22 |
| Processing | ($ per lb.) | 0.74 | 0.69 | 0.59 | 0.51 | 0.50 |
| Smelter operating cost | ($ per lb.) | 0.51 | 0.41 | 0.27 | 0.01 | - |
| Logistics charges | ($ per lb.) | 0.29 | 0.24 | 0.22 | 0.70 | 0.38 |
| Refining and treatment charges | ($ per lb.) | 0.08 | 0.08 | 0.12 | 0.13 | 0.21 |
| Sulphuric acid credits | ($ per lb.) | (0.69) | (0.39) | (0.32) | - | - |
| General & Administrative | ($ per lb.) | 0.41 | 0.35 | 0.31 | 0.42 | 0.31 |
| Cash cost (C1) | ($ per lb.) | 3.00 | 2.84 | 2.58 | 2.99 | 2.62 |
Units in U.S. dollars per payable pound of copper in saleable product produced
The cost of power, which is allocated between mining, processing and smelting in the above cash cost split, can be split out as follows:
| Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | ||
| Power costs | ($ per lb.) | 0.69 | 0.57 | 0.47 | 0.33 | 0.35 |
| Power costs as a proportion of total cash cost (C1) | (%) | 23.0% | 20.1% | 18.2% | 11.0% | 13.4% |
Units in U.S. dollars per payable pound of copper in saleable product produced.
Cash cost (C1) is prepared on a basis consistent with the industry standard definitions by Wood Mackenzie cost guidelines, but is not a measure recognized under IFRS Accounting Standards. In calculating the C1 cash cost, the costs are measured on the same basis as the company's share of profit from the Kamoa Holding joint venture, which is contained in the financial statements. C1 cash cost is used by management to evaluate operating performance and includes all direct mining, processing, and general and administrative costs. Smelter charges and freight deductions on sales to the final port of destination, which are recognized as a component of sales revenues, are added to C1 cash cost to arrive at an approximate cost of delivered, finished metal. C1 cash cost excludes royalties, production taxes, and non-routine charges as they are not direct production costs.
All figures are on a 100% project basis, and metal reported in concentrate is before refining losses or deductions associated with smelter terms.
Year-to-date, Kamoa-Kakula has produced 212,146 tonnes of contained copper at a cash cost (C1) of $2.80/lb.
Copper production at Kamoa-Kakula totalled 212,146 tonnes in saleable products, including 180,991 tonnes of copper in anode produced by the Kamoa-Kakula smelter, 12,349 tonnes of toll-treated copper in blister at the nearby Lualaba Copper Smelter (LCS), 11,903 tonnes of copper in slag concentrate produced by the Kamoa-Kakula smelter and 6,904 tonnes of copper fines designated for sale.
Summary of quarterly production data from Kamoa-Kakula
| Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | |
| Phase 1 & 2 | |||||
| Ore milled (000's tonnes) | 1,820 | 1,387 | 1,534 | 1,712 | 1,838 |
| Feed grade of ore processed (% copper) | 2.36% | 2.59% | 2.35% | 2.32% | 2.50% |
| Copper recovery (%) | 88.9% | 86.6% | 84.1% | 83.2% | 81.3% |
| Copper in concentrate produced (tonnes) | 38,523 | 30,211 | 30,527 | 34,602 | 37,744 |
| Phase 3 | |||||
| Ore milled (000's tonnes) | 1,673 | 1,582 | 1,574 | 1,662 | 1,618 |
| Feed grade of ore processed (% copper) | 2.07% | 2.22% | 2.28% | 2.38% | 2.44% |
| Copper recovery (%) | 86.0% | 88.2% | 87.2% | 88.2% | 84.2% |
| Copper in concentrate produced (tonnes) | 29,664 | 30,923 | 31,379 | 34,814 | 33,522 |
| Combined Phase 1, 2 and 3 | |||||
| Ore milled (000's tonnes) | 3,493 | 2,968 | 3,108 | 3,374 | 3,456 |
| Feed grade of ore processed (% copper) | 2.22% | 2.39% | 2.32% | 2.35% | 2.47% |
| Copper recovery (%) | 87.6% | 87.4% | 85.6% | 85.7% | 82.7% |
| Copper in concentrate produced (tonnes) | 68,188 | 61,134 | 61,906 | 69,416 | 71,266 |
| Smelter | |||||
| Contained copper in anode, blister or concentrate (tonnes)(1) | 76,401 | 64,328 | 71,417 | - | - |
| High-strength sulphuric acid (tonnes) | 118,638 | 112,307 | 117,871 | - | - |
Data in BOLD denotes a quarterly record.
(1) Copper production in anode and blister produced consists of copper production from Kamoa-Kakula's on-site smelter, as well as toll-treated Kamoa-Kakula concentrate at the LCS smelter in Kolwezi. Production also includes slag concentrate produced by Kamoa-Kakula's smelter that is sold to third parties and not reprocessed by either the on-site smelter or by LCS.
Kamoa-Kakula 2026 production is expected to be approximately 290,000 tonnes of copper in saleable products.
At the start of Q3 2026, Kamoa-Kakula had approximately 40,000 tonnes of unsold copper held in inventory. At the end of Q3 2026, Kamoa-Kakula had approximately 43,000 tonnes of copper in inventory. Unsold copper stockpiles mainly consisted of unsold copper in concentrates held on-site and at LCS, copper in the smelter circuit, as well as copper in off-spec concentrates, including slag concentrate and high-grade copper fines. Year-end copper inventories are now expected to be between 35,000 and 40,000 tonnes of copper.
During the quarter, Kamoa-Kakula assayed, surveyed and tendered for sale 6,904 tonnes of high-grade copper fines, which were also added to copper held in inventory. High-grade copper fines are previously produced and stockpiled materials that were unable to be smelted and have been designated for sale to third parties. Sales of the copper fines are expected to start in the fourth quarter.
Updated Kamoa-Kakula life-of-mine plan on track for completion in March 2027; short-term 2027 copper production and cash cost guidance revised
Following the release of the Kamoa-Kakula 2025 Mineral Reserve and Mineral Resource Estimate on March 31, 2026, work immediately began on the updated life-of-mine plan, which is on track for completion in March 2027.
Since early Q2 2026, a significant amount of work has been completed including an in-fill drilling campaign and engineering trade-off studies. Data from this work has provided sufficient foundation to update the geological, hydrological and geotechnical models for both Kamoa and Kakula.
From the work completed to date, the maximum capacity of the Phase 1, 2 and 3 concentrators under the revised parameters, excluding the future Phase 4 concentrator, has been lowered to 400,000 to 450,000 tonnes of copper in saleable products. In addition, a slower-than-expected ramp-up is expected in 2027, with production guidance for 2027 lowered to 300,000 to 350,000 tonnes of copper in saleable products and the cost guidance increased to $2.50 to $3.00 per payable pound of saleable copper produced. The slower ramp-up in 2027 is mainly due to a delay in the start of stoping on the Eastern side of Kakula from Q4 2027 to late Q1 2028 and a reduction in the estimated maximum mining rate at Kakula.
The combined processing capacity of the Phase 1, 2 and 3 concentrators is expected to be fully utilized from mid-2027, albeit at lower average grades than previously guided. The ore sources that make up the 2027 and mid-term guidance are shown in Figure 1. As new data becomes available from additional drilling and engineering work into 2027, further refinements to the mine plans will be made.
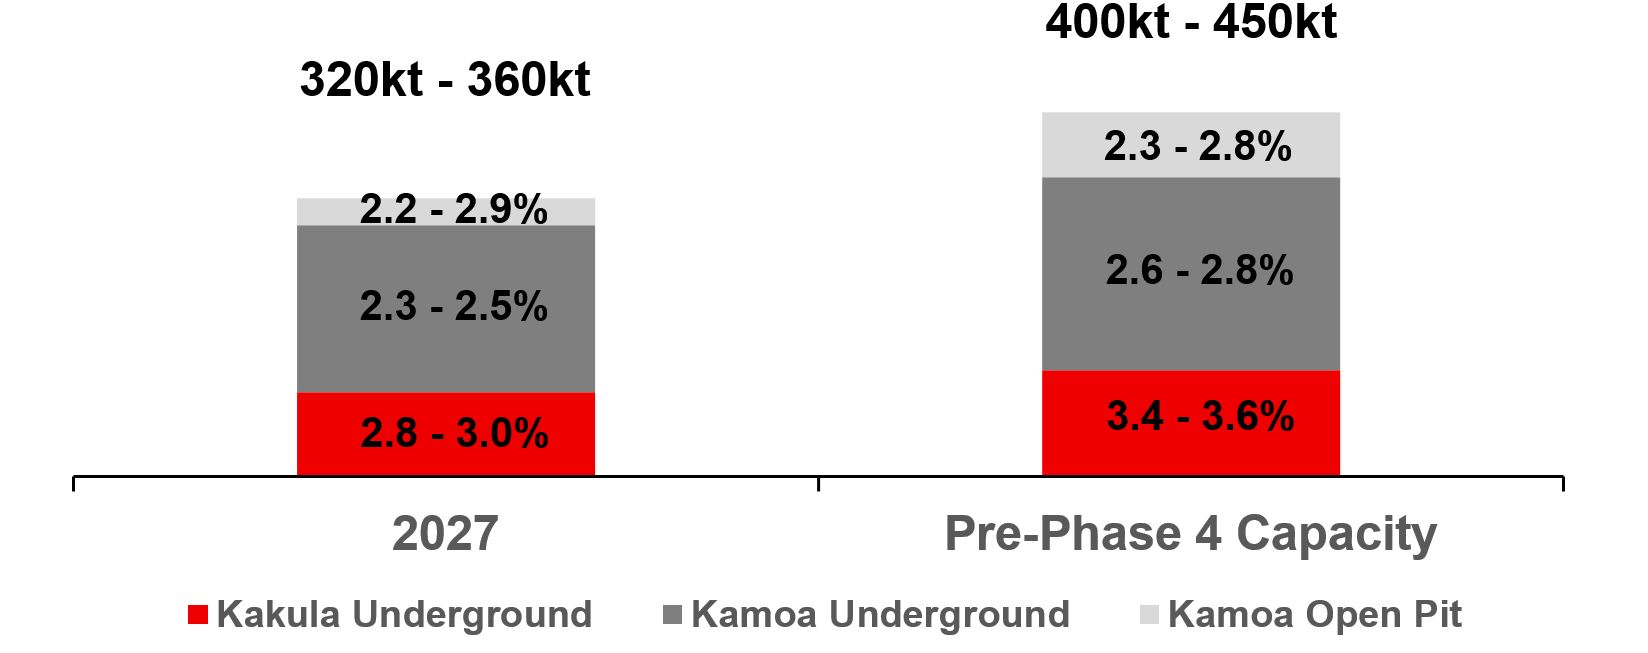
Figure 1. Kamoa-Kakula 2027 copper production guidance and pre-Phase 4 outlook, by mined ore source (tonnes) and expected head grades (% copper).
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_q3.jpg
Future of the Kamoa-Kakula Copper Complex to include mining from open pits to support underground operations; pre-stripping of Kamoa open pits to commence in Q1 2027
Open-pit mining is expected to provide a scalable source of ore for the Phase 1, 2 and 3 concentrators, as well as the future Phase 4 concentrator, improving the operational flexibility of the Kamoa-Kakula Copper Complex.
Pre-stripping of two starter pits at Kamoa is expected to commence in Q1 2027, with first ore targeted for mining in Q3 2027. By the end of 2028, approximately 3.5 million tonnes of ore at an average grade of 2.5% is expected to have been mined from the open pits. Pre-stripping of two additional starter pits at Kamoa will start by the end of 2028.
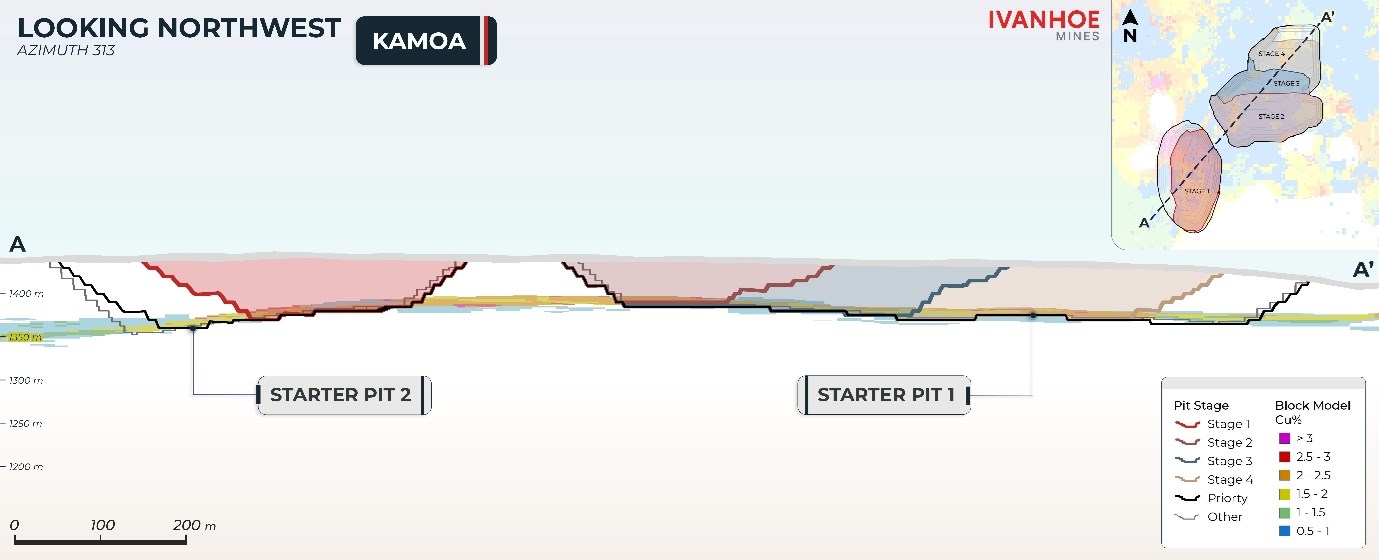
Figure 2. Section view of the Kamoa starter pits 1 & 2, overlaid with the Kamoa block model.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_bbd1221624ca7948_013full.jpg
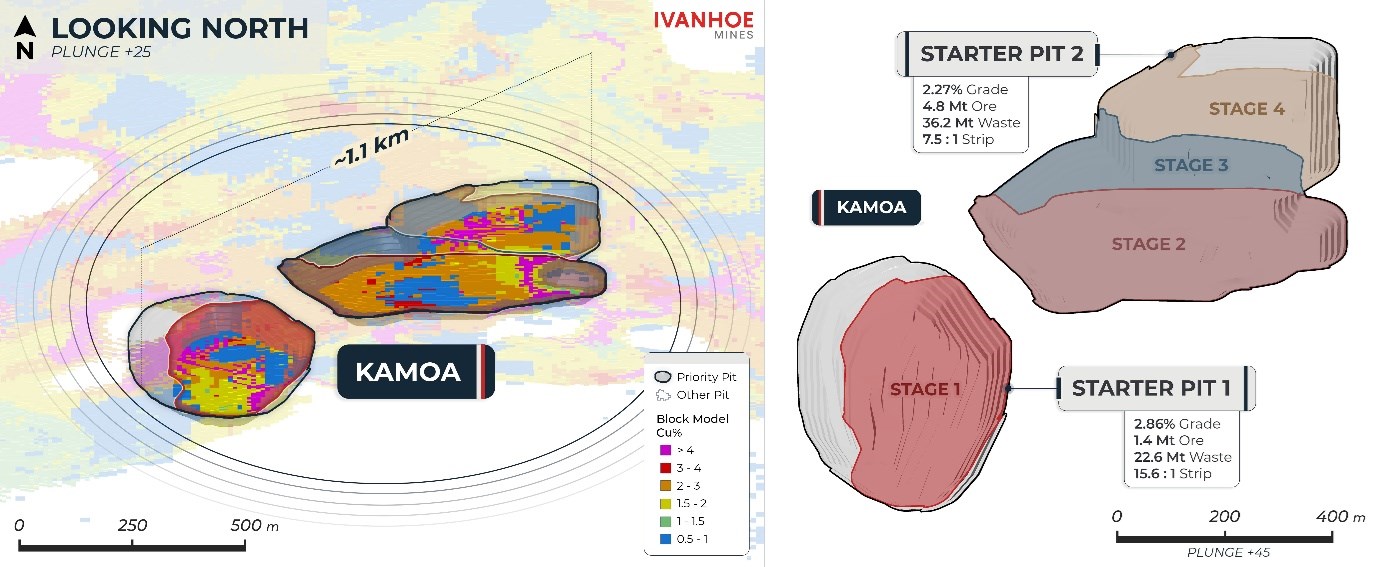
Figure 3. Isometric view of the planned starter open pits, overlaid with the Kamoa block model.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_bbd1221624ca7948_014full.jpg
Where amenable, open-pit mining is a lower-cost extraction method compared with the current underground mining methods used across the complex. Therefore, the grade of economically extractable Mineral Resources can be lowered, potentially unlocking portions of shallow copper mineralization at Kamoa that were previously excluded from underground mine designs and Mineral Reserves.
The cut-off grade for the open-pit mined ore will be reduced from the current 1.5% to 2.0% copper, to as low as 0.4% copper. While open-pit mining lowers the overall head-grade, it is a less capital-intensive way of increasing the mining rate and also increasing the overall orebody extraction ratio from approximately 65% as per the current underground mining method, up to approximately 95%.
The introduction of open-pit mining has therefore influenced the timing around the introduction of the Phase 4 expansion, as the lower-grade feed requires additional processing capacity to produce sufficient concentrate to fill the on-site copper smelter.
Phase 4 expansion to increase production capacity of Kamoa-Kakula to approximately 500,000 tonnes per annum; detailed design on Phase 4 concentrator to commence in Q1 2027
Since inception, Kamoa-Kakula's project development has consisted of a multi-phased expansion plan. The Phase 1 concentrator was completed and commissioned in 2021, ahead of schedule and on budget, for an initial capital expenditure of $1.3 billion. The Phase 2 expansion was completed the following year, also ahead of schedule and on budget, doubling Kamoa-Kakula's processing capacity with an additional capital investment of $0.7 billion. Phase 1 and 2 concentrators were identical and built adjacent to one another near the Kakula North portal. Phase 1's capital expenditure was 85% higher than Phase 2's because the stockpiling, materials handling, crushing, and screening capacity, as well as other associated infrastructure, required for the Phase 2 concentrator was pre-built during Phase 1 construction.
Kamoa-Kakula’s last expansion, Phase 3, which was also completed ahead of schedule and on budget in June 2024, consisted of a larger processing plant and associated underground mine expansion at Kamoa with a total capital expenditure of $2 billion. The Phase 3 concentrator, which was built between the Kansoko and Kamoa 1 portals, has a 30% larger capacity than that of Phase 1 and 2.
The Kamoa-Kakula project team adopted a similar strategy for Phase 3, as for Phase 1, with preparations made during construction for the next expansion phase to be built adjacent to it. The foundations for the future Phase 4 concentrator, as well as materials-handling infrastructure, including the run-of-mine (ROM) stockpile and reclaimer, conveyors, and screening and crushing circuits, have already been built. The future Phase 4 expansion is expected to include an additional similar-sized concentrator. In addition, since the completion of the Phase 3 expansion, construction of Cell 2 of the tailings storage facility (TSF) was completed earlier this year, which was originally part of Phase 4.
The capital intensity of Phases 1, 2, and 3 totals approximately $9,800 per tonne of annualized copper production, as shown in Figure 4. Based on preliminary estimates, the Phase 4 expansion is expected to add an additional 5.0 - 6.5 million tonnes per annum of concentrator capacity, increasing total complex processing capacity from 17 million tonnes today to 22.0-23.5 million tonnes per annum. The Phase 4 expansion is expected to have a capital intensity of approximately $9,000-$12,000 per tonne of annualized copper production, including development of the supporting open pit operations. The capital intensity compares favorably with peer brownfield projects, based on the data in Figure 4.
The Phase 4 expansion is expected to sustain Kamoa-Kakula's copper production at approximately 500,000 tonnes per annum. The construction timeline to deliver the Phase 4 expansion is expected to be 18-24-months from approval. Detailed engineering on the Phase 4 concentrator is also expected to commence in Q1 2027.
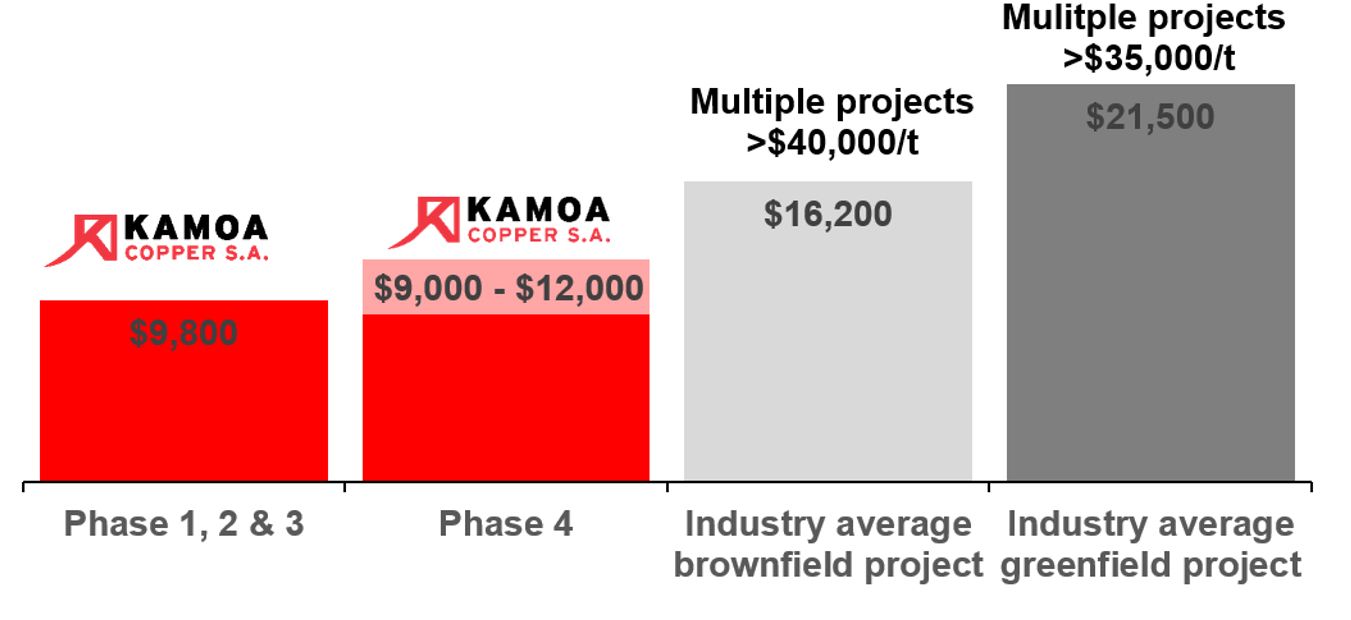
Figure 4. Achieved capital intensity of Kamoa-Kakula's Phase 1, 2 and 3, alongside initial estimates for the capital intensity of the Phase 4 expansion, as well as greenfield and brownfield copper industry peers (initial capital expenditure per tonne of annualized copper production)
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_q3_2.jpg
Source: Industry-average data taken from Wood Mackenzie research, as of November 3, 2026. Kamoa-Kakula data consists of Phase 1, 2 & 3 total capex of $4.4 billion and annualized copper production of 450,000 tonnes. Phase 1, 2 & 3 capital includes the debottlenecking program and excludes Project 95, DRC grid power infrastructure improvements, refurbishment of DRC hydroelectric power facilities, and the on-site copper smelter. Phase 4 capital intensity is based on indicative internal estimates for capital and production.
Copper production in Q3 2026 continued to improve; supported by a 20% quarter-on-quarter increase in mining rates across the complex as tonnes mined from stoping increased by 84%
During Q3 2026, mining rates across the complex increased quarter-on-quarter by 20% to over 1.2 million tonnes per month, equivalent to approximately 14.4 million tonnes per annum (Mtpa). The increase was driven by the mobilization of additional mining crews, a new box-cut access into the Kamoa 1 Mine, and an 84% increase in stoping (production mining).
In Q2 2026, construction of a new box cut to access the Kamoa 1 Mine was completed. The new 'Kahala' box cut decline has been developing in ore since June 2026.
The Phase 1 and 2 concentrators milled 30% more ore than the prior quarter, driven predominantly by additional ore supplied from Kakula and Kansoko. By quarter end, approximately 50% of the Phase 1 and 2 concentrator feed was from the western side of Kakula, with the remaining ore from the Kansoko mine.
Copper recoveries from the Phase 1 and 2 concentrators have notably improved with the introduction of Project 95. Prior to the completion of Project 95, copper recoveries from Phase 1 and 2 averaged 83% to 85%. Following the completion of Project 95 at the end of the second quarter, copper recoveries have improved, averaging 89% during Q3. Since quarter-end, a record 92% copper recovery was achieved over two weeks in mid-October.
On-site, 500,000 tonnes-per-annum copper smelter remains at 60% of design capacity; local demand for smelter's high-strength sulphuric acid continues to benefit from global supply chain disruptions
In line with concentrate production, the 500,000 tonnes-per-annum smelter continues to operate at approximately 60% of design capacity. In addition to copper anodes, the smelter produces high-strength sulphuric acid at an average rate of approximately 1,250 tonnes per day. This is equivalent to an annualized rate of approximately 450,000 tonnes per annum, compared with the design capacity of 700,000 tonnes per annum. Kamoa-Kakula sells sulphuric acid from the mine gate to nearby mining operations on the DRC Copperbelt that use it to leach copper and cobalt metal from oxide ores.
In the third quarter, the Kamoa-Kakula smelter produced a record 118,638 tonnes of high-strength sulphuric acid. The average net realized price for high-strength sulphuric acid sales during Q3 2026 approximately doubled, compared with the prior quarter, to approximately $915 per tonne. Average net realized prices for high-strength sulphuric acid during September and October were approximately $950 per tonne. Sulphuric acid prices are expected to remain elevated over the short term, with 3-month contracts starting in November at a set realized price of approximately $900 per tonne.
A 35-day shutdown of the smelter is planned in H1 2027 for safety and efficiency upgrades.
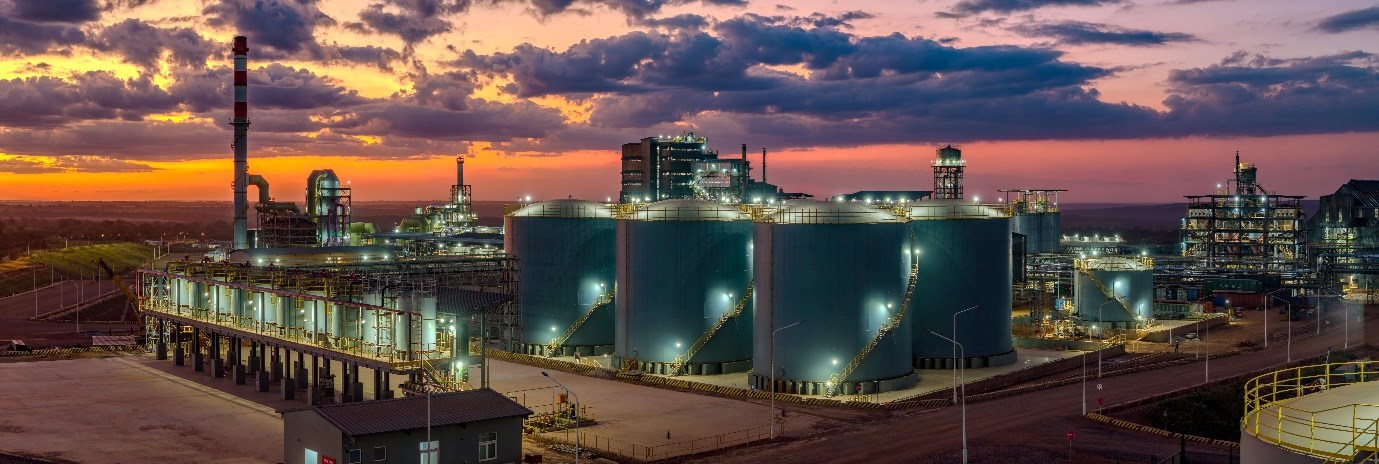
Sunset over the acid storage and load-out facility at Kamoa-Kakula’s 500,000-tonnes-per-annum copper smelter. The smelter is currently operating at 60% of capacity.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_bbd1221624ca7948_016full.jpg
Kamoa-Kakula's on-site hybrid solar facility with battery storage is fully operational, delivering 60 megawatts (MW) of continuous baseload power; power purchase agreements signed to double on-site hybrid solar capacity to 120 MW within 18 months
During the third quarter, construction and commissioning of Kamoa-Kakula's on-site solar photovoltaic (PV) facilities, with battery energy storage system (BESS), was completed. By quarter end, both facilities were fully ramped up and operating at their combined nameplate capacity, delivering 60 MW of continuous baseload power to Kamoa-Kakula's operations.
Construction of the two 30-MW facilities started in June 2025. The first 30-MW facility began delivering power in August 2026, and the second became operational in late September. Each 30-MW facility is owned, operated and funded by CrossBoundary Energy and Green World Energie.
Power generated by the combined 433-MW (peak capacity) PV facility is stored in the adjacent 1,107-megawatt-hour (MWh) battery storage facility. The facility delivers baseload power to Kamoa-Kakula's operations, the sole offtaker, at a continuous rate of 60 MW over 24 hours. Together, the facilities are the largest hybrid solar installation at a mining operation in Africa, and therefore the largest of their kind.
Kamoa-Kakula is advancing plans to double the on-site hybrid solar PV power capacity, with BESS, to 120 MW within 18 months. In April 2026, Kamoa-Kakula awarded a contract and signed a 30-MW power purchase agreement (PPA) with Green World Energie. Kamoa-Kakula also awarded a further contract and signed a 30-MW power purchase agreement (PPA) with Lualaba Solar Company in August 2026. Both new facilities will also be constructed on Kamoa-Kakula's joint-venture licence area, near the Phase 1 and 2 concentrators.
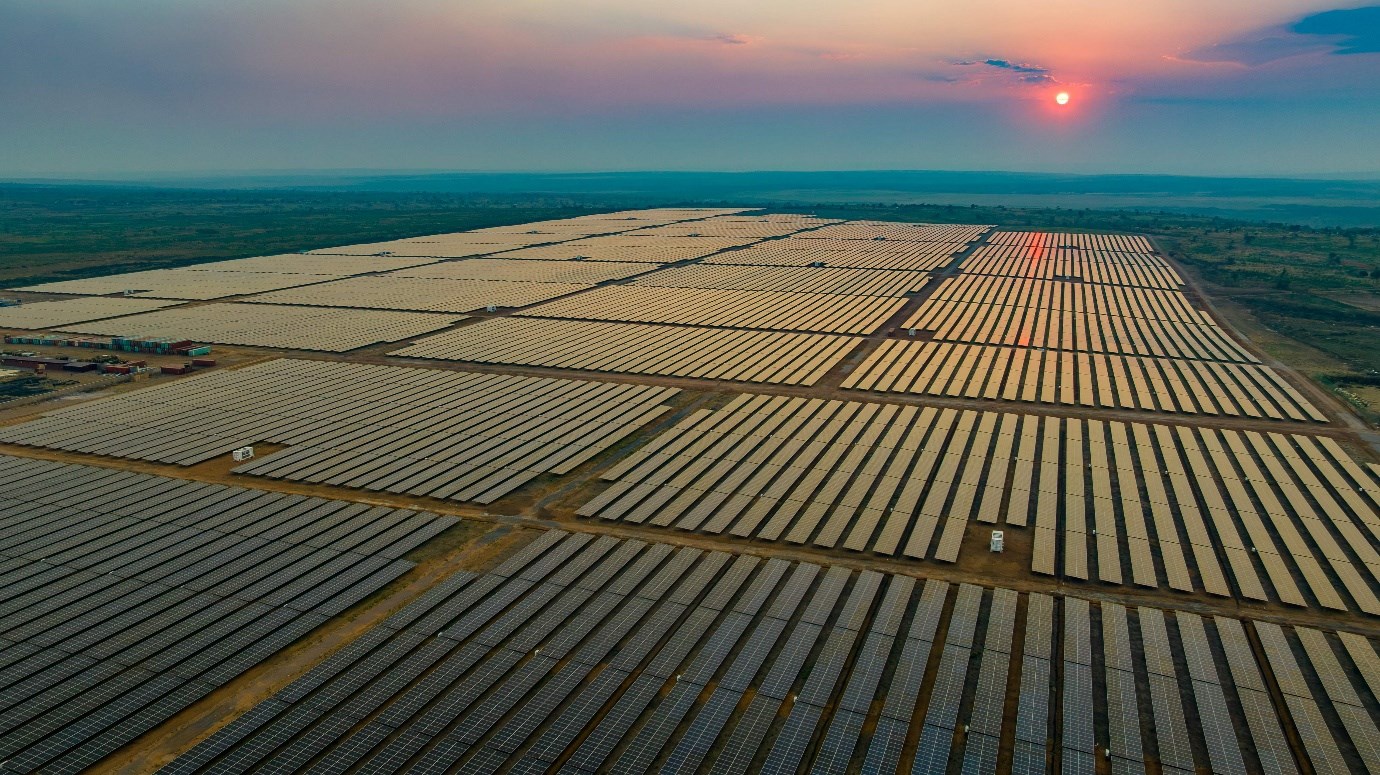
View over the new on-site hybrid solar facility, which fully ramped up to full capacity in September, delivering 60 MW of continuous baseload power to Kamoa-Kakula's operations. The facility is the largest hybrid solar PV facility with battery storage installed at a mine site on the African continent.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_bbd1221624ca7948_017full.jpg
Ramp up of on-site solar power facilities in September reduces reliance on back-up generators for dewatering, reducing costs by $0.10/lb. to $0.20/lb.
At the end of the second quarter, approximately 50% of on-site diesel consumption was used by the on-site back-up diesel-powered generators. The generators are more reliable than grid power for maintaining pumping operations across the complex.
With the on-site hybrid solar facility now complete, the reliance on the backup diesel generators will decrease significantly. In the third quarter, approximately 12 MW of back-up generator power was dedicated for pumping operations. In mid-October, the pumping infrastructure, previously powered by the backup generators, was transferred to the solar facility.
Going forward, the solar facility is expected to save approximately $0.10/lb. to $0.20/lb. in power costs, compared with using the on-site diesel generators
COPPER PRODUCTION, CASH COST AND CAPITAL EXPENDITURE GUIDANCE
| Kamoa-Kakula Guidance | 2026 | 2027 |
| Contained copper in saleable products (tonnes)(1) | ~290,000 | 300,000 - 350,000 (prev. 380,000 - 420,000) |
| Cash cost (C1) ($ per lb.)(2) | 2.60 - 3.00 | 2.50 - 3.00 (prev. 2.10 - 2.50) |
| Capital expenditure ($ million)(3) | 1,100 - 1,200 (prev. 1,100 - 1,400) | 950 - 1,150 (prev. 750 - 950) |
(1) 2026 production guidance range previously 290,000 to 310,000 tonnes of copper in anode or blister
(2) US dollars per payable pound of copper in saleable product produced
(3) Capital expenditure excludes capitalized pre-stripping estimated to be $100 million to $200 million.
Guidance figures are on a 100% project basis and metal reported in concentrate is before refining losses associated with smelter terms.
Kamoa-Kakula 2026 production is expected to be approximately 290,000 tonnes of copper in saleable products.
Kamoa-Kakula's guidance is based on several assumptions and estimates. It involves estimates of known and unknown risks, uncertainties, and other factors that may cause the actual results to differ materially.
The turnaround of the Kakula Mine is advancing; however, risk factors remain. The risk factors include the integrity of underground infrastructure. Construction of new de-watering infrastructure is now underway and will be required for access to new mining areas within the required timeline and to deliver the planned ramp-up of underground operations in line with expectations. Risk factors also include the mobilization of the open pit contractors in Q1 2027 and the timely approval of new mine plans by the joint venture. Kamoa-Kakula guidance is based on an assessment of these factors that management believes are reasonable at this time, given all available information.
2026 and 2027 production and cash cost (C1) guidance includes updated mine designs at both the Kamoa and Kakula mines which include a longer period of up-front development to support a more sustainable future rate of mining. Development will be focused over the next 12 to 18 months to complete more peripheral development around the Kakula Mine before stoping of the newly developed areas begins. Stoping started at Kamoa in Q2 2026, stoping at Kakula is not expected until late Q1 2028.
Cash cost (C1) guidance is based primarily on assumptions, including tonnes of ore mined, feed grades of processed copper ore, concentrator recoveries, as well as the timing and ramp-up of the on-site smelter, and the cost of diesel among other variables.
Cash cost (C1) is a non-GAAP measure used by management to evaluate operating performance and includes all direct mining, processing, stockpile rehandling, and general and administrative costs. Smelter charges and freight deductions on sales to the final port of destination (predominantly China), which are recognized as a component of sales revenues, are added to cash cost (C1) to arrive at an approximate cost of delivered finished metal.
Kamoa-Kakula’s 2026 capital expenditure guidance is trending towards the lower end of the range. The capital expenditure guidance range for Kamoa-Kakula has been updated to reduce the upper end of the 2026 guidance by $200 million and to defer that and include it in the 2027 guidance range. The 2027 capital expenditure guidance excludes estimated capital expenditure for open pit mining at Kamoa estimated to be $100 million to $200 million.
For historical comparatives and a reconciliation to the most directly comparable measure under IFRS, see the non-GAAP Financial Performance Measures section of this release and the company's MD&A for the three and nine months ended September 30, 2026.
2. Kipushi Mine
62%-owned by Ivanhoe Mines
Democratic Republic of the Congo
The ultra-high grade Kipushi underground zinc-copper-germanium-silver-lead mine in the DRC is located adjacent to the town of Kipushi on the Zambian border, approximately 30 kilometres southwest of the city of Lubumbashi on the Central African Copperbelt. The Kipushi Mine is approximately 250 kilometres southeast of the Kamoa-Kakula Copper Complex.
Ivanhoe acquired a 68% interest in the Kipushi Mine in November 2011. The DRC state-owned mining company, Gécamines, held the remaining 32% in the Kipushi Mine. Following the updated joint venture agreement signed in late 2023, Gécamines' ownership has since increased to 38%.
The Kipushi Mine was restarted in mid-2024, after 32 years of being placed on care and maintenance. Over the following 2 years, operations have consistently ramped up quarter on quarter. In 2026, the Kipushi Mine is set to become the world's third-largest and highest-grade zinc mine. Kipushi's full-time employee workforce is approximately 1,303, with over 87% being Congolese.
Kipushi summary of operating and financial data
| Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | |
| Ore tonnes milled (tonnes) | 193,581 | 200,774 | 196,774 | 194,140 | 168,862 |
| Feed grade of ore milled (% zinc) | 41.58% | 38.71% | 36.96% | 36.18% | 37.81% |
| Zinc recovery (%) | 96.02% | 91.91% | 90.63% | 87.71% | 89.36% |
| Zinc in concentrate produced (tonnes) | 77,147 | 70,177 | 65,044 | 61,444 | 57,200 |
| Payable zinc sold (tonnes)(1) | 69,384 | 43,424 | 54,940 | 48,075 | 49,744 |
| Cost of sales per pound ($ per lb.) | 1.14 | 1.06 | 1.06 | 1.13 | 1.11 |
| Cash cost (C1) ($ per lb.)(2) | 0.91 | 0.90 | 0.86 | 0.86 | 0.95 |
| Realized zinc price ($ per lb.) | 1.73 | 1.58 | 1.47 | 1.44 | 1.27 |
| Sales revenue before remeasurement ($'000) | 242,512 | 137,413 | 160,142 | 133,792 | 126,855 |
| Remeasurement of contract receivables ($'000) | 12,066 | 8,872 | 1,400 | 4,246 | 2,548 |
| Sales revenue after remeasurement ($'000) | 254,578 | 146,285 | 161,542 | 138,038 | 129,403 |
| EBITDA ($'000) | 108,346 | 50,907 | 58,485 | 44,211 | 26,674 |
| EBITDA margin (% of sales revenue) | 43% | 35% | 36% | 32% | 21% |
Data in BOLD denotes a quarterly record.
All figures in the above tables are on a 100%-project basis. Metal reported in concentrate is before refining losses or deductions associated with smelter terms. This release and the company's MD&A includes "EBITDA", "Adjusted EBITDA", "EBITDA margin", "Pro-rata cash and cash equivalents" and "Cash cost (C1)", which are non-GAAP financial performance measures. For a detailed description of each of the non-GAAP financial performance measures used herein and a detailed reconciliation to the most directly comparable measure under IFRS Accounting Standards, please refer to the non-GAAP Financial Performance Measures and Pro-Rata Financial Ratios sections of this release and the company's MD&A for the three and nine months ended September 30, 2026.
(1) Payable zinc in concentrate sold is net of standard 85% payability.
(2) Units in U.S. dollars per payable pound of zinc sold.
Kipushi cash cost (C1) breakdown:
| Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | Q3 2025 | ||
| Mining | ($ per lb.) | 0.15 | 0.19 | 0.17 | 0.18 | 0.18 |
| Processing | ($ per lb.) | 0.12 | 0.07 | 0.07 | 0.09 | 0.05 |
| Logistics charges | ($ per lb.) | 0.52 | 0.50 | 0.46 | 0.44 | 0.49 |
| Treatment charges | ($ per lb.) | 0.05 | 0.06 | 0.07 | 0.07 | 0.07 |
| Support services | ($ per lb.) | 0.07 | 0.08 | 0.09 | 0.08 | 0.16 |
| Cash cost (C1) per pound of payable zinc sold | ($ per lb.) | 0.91 | 0.90 | 0.86 | 0.86 | 0.95 |
Units in U.S. dollars per payable pound of payable zinc sold
Cash cost (C1) is prepared on a basis consistent with the industry standard definitions by Wood Mackenzie cost guidelines but cash cost per pound for the Kipushi Mine has been presented on a per tonne sold basis to eliminate the impact of unsold tonnes of zinc concentrate in inventory. Cash cost (C1) and cash cost per pound are not measures recognized under IFRS Accounting Standards. C1 cash cost is used by management to evaluate operating performance and includes all direct mining, processing, and general and administrative costs. Smelter charges and freight deductions on sales to the final port of destination, which are recognized as a component of sales revenues, are added to C1 cash cost to arrive at an approximate cost of delivered, finished metal. C1 cash cost excludes royalties, production taxes and non-routine charges as they are not direct production costs.
All figures are on a 100% project basis and metal reported in concentrate is before refining losses or deductions associated with smelter terms.
Kipushi concentrator produced a record 77,147 tonnes of zinc in Q3 2026, a quarter-on-quarter increase of 10%; production tracking towards the upper end of 2026 guidance
The Kipushi concentrator produced a record 77,147 tonnes of zinc in concentrate in Q3 2026, up 10% quarter-on-quarter and equivalent to an annualized zinc production of approximately 309,000 tonnes. The quarterly performance was boosted by 193,581 tonnes of ore milled, a record feed grade of 41.6% zinc and a record concentrator recovery of 96%. In addition, the Kipushi concentrator produced a record 26,560 tonnes of zinc in July.
Kipushi’s Q3 2026 production marks the seventh consecutive quarter-on-quarter increase in zinc production, as shown in Figure 5. With full-year zinc production trending towards the top end of the guidance range, Ivanhoe Mines tightens the Kipushi Mine’s 2026 production guidance to 270,000 to 290,000 (previously 240,000 to 290,000) tonnes of zinc in concentrate, which is expected to rank Kipushi among the top three zinc mines in the world.
Higher cash costs (C1) during the quarter, compared with Q2 2026, were mainly driven by higher diesel prices, which affected processing and logistics costs, and by additional logistics charges arising from customs clearance and transportation bottlenecks.
Inventory of unsold zinc concentrate decreased to 42,000 tonnes of contained zinc, from 44,000 tonnes in Q2 2026. On-site inventory at Kipushi decreased from 16,000 to 9,000 tonnes, while zinc in concentrate inventory in transit increased from 28,000 to 33,000 tonnes.
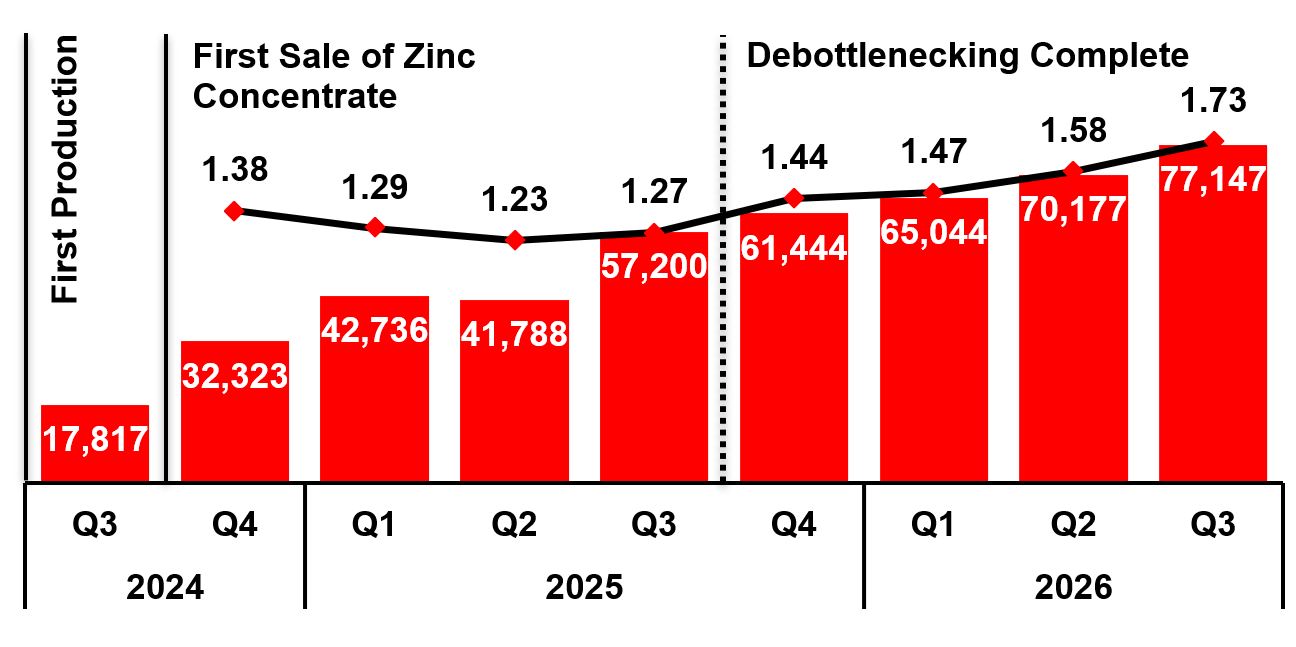
Figure 5. Quarterly zinc in concentrate produced by the Kipushi concentrator (tonnes) & the realized zinc price (US$ per pound). The Q3 2026 production rate annualized is equivalent to 309,000 tonnes of zinc in concentrate.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_q3_3.jpg
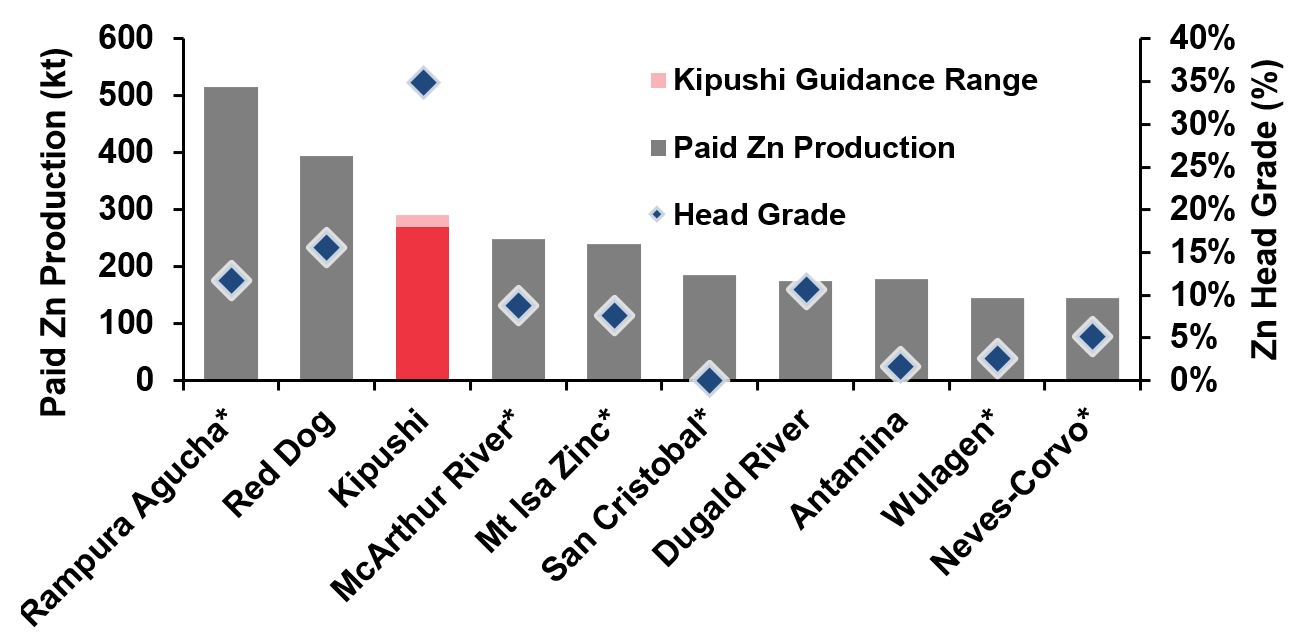
Figure 6. World's top 10 zinc mines by contained zinc production ('000 tonnes), with head grade (% zinc). Kipushi is on track to meet 2026 production guidance, placing it among the top 3 zinc mining operations.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_q3_4.jpg
Notes. Source: Company Data, S&P Capital IQ on October 28, 2026.
*Denotes that company guidance not provided, in its place 2025 paid zinc production used as per S&P Capital IQ, 2026. Lanping Jinding excluded. Production for Kipushi is the 2026 guidance range as disclosed on November 3, 2026
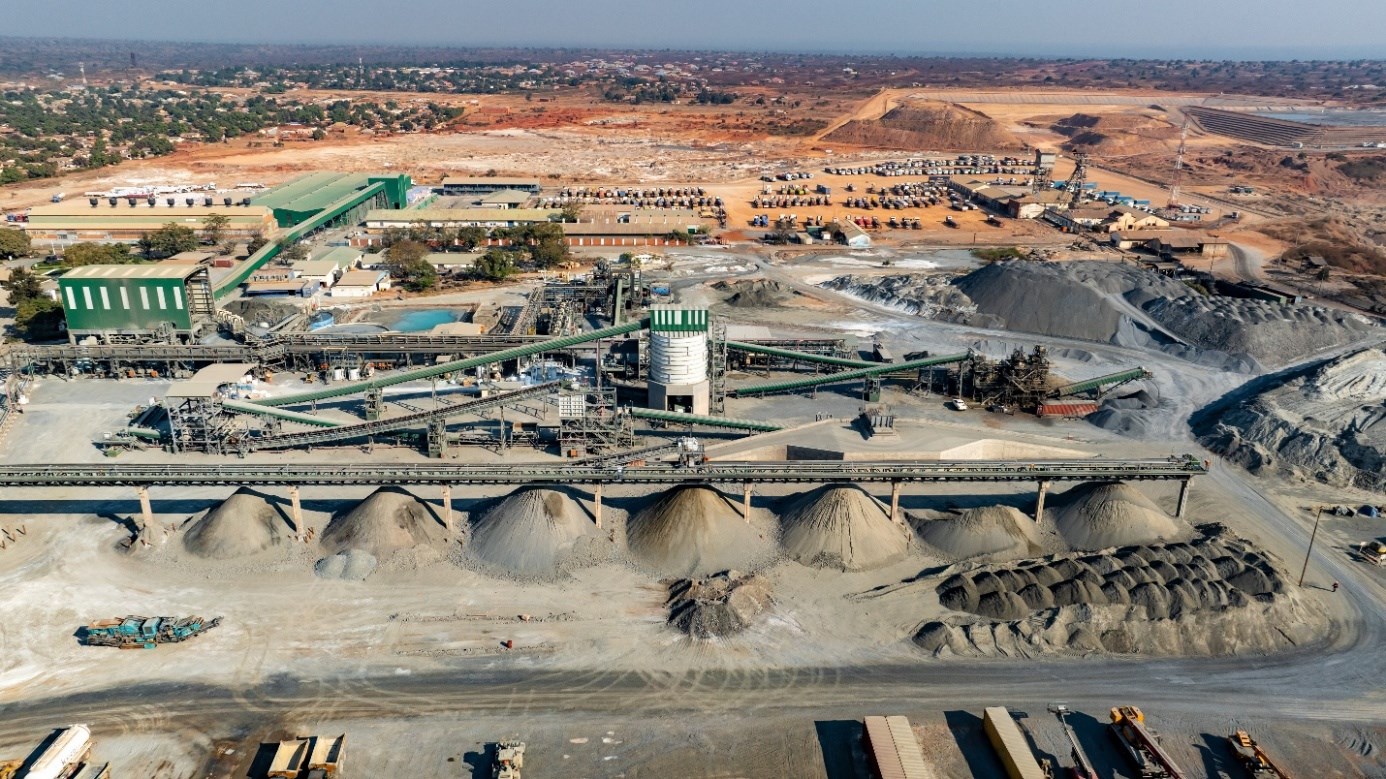
Aerial view over Kipushi's 960,000-tonnes-per-annum concentrator, with the run-of-mine stockpiles of ultra-high-grade zinc ore in the foreground.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_bbd1221624ca7948_026full.jpg
Following the success of the hybrid solar PV facility at Kamoa-Kakula, a similar facility is planned to support the Kipushi operations. The tender for the facility is currently undergoing adjudication, with project award expected in the fourth quarter. The facility will be designed to provide 10 MW of continuous baseload power, providing approximately 50% of the Kipushi Mines' energy requirements. The facility is expected to be commissioned and operational in Q2 2028.
Since quarter-end, Kipushi has been supported by an additional 10 MW of grid-supplied power from third-party providers. The additional power is expected to reduce power instability experienced by Kipushi's operations and reduce power costs associated with the backup diesel generators.
In the fourth quarter, Kipushi Corporation is expected to upstream excess cash from the DRC subsidiary to Ivanhoe Mines.
ZINC PRODUCTION, CASH COST AND CAPITAL EXPENDITURE GUIDANCE FOR 2026
| Kipushi 2026 Guidance | Previous | New |
| Contained zinc in concentrate (tonnes) | 240,000 - 290,000 | 270,000 - 290,000 |
| Cash cost (C1) ($ per pound)(1) | 0.85 - 0.95 | unchanged |
| Capital expenditure ($ million) | 60 | unchanged |
Guidance figures are on a 100% project basis.
(1) Cash cost (C1) is US dollars per pound of payable zinc sold
Kipushi's guidance is based on several assumptions and estimates of known and unknown risks, uncertainties, and other factors that may cause the actual results to differ, including the reliability of DRC grid power supply and prevailing logistics rates, among other variables. Metal reported in concentrate is before treatment losses or payability deductions associated with smelter terms.
Cash cost (C1) is a non-GAAP measure used by management to evaluate operating performance and includes all direct mining, processing, stockpile rehandling charges, and general and administrative costs. Smelter charges and freight deductions on sales to the final port of destination, which are recognized as a component of sales revenues, are added to cash cost (C1) to arrive at an approximate cost of delivered finished metal.
For historical comparatives and a reconciliation to the most directly comparable measure under IFRS see the non-GAAP Financial Performance Measures section of this release and the company's MD&A for the three and nine months ended September 30, 2026.
3. Platreef Mine
64%-owned by Ivanhoe Mines
South Africa
The Platreef Mine is located on the Northern Limb of the Bushveld Igneous Complex in Limpopo Province - approximately 280 kilometres northeast of Johannesburg and eight kilometres from the town of Mokopane in South Africa. The project is owned by Ivanplats (Pty) Ltd. (Ivanplats), which is 64%-owned by Ivanhoe Mines. A 26% interest is held by Ivanplats' historically disadvantaged, broad-based, black economic empowerment (B-BBEE) partners, which include 20 local host communities with approximately 150,000 people, project employees, and local entrepreneurs. The remaining 10% interest is held by a Japanese consortium, consisting of ITOCHU Corporation, Japan Organization for Metals and Energy Security (JOGMEC), and Japan Gas Corporation.
Platinum-group metals (PGM) mineralization in the Northern Limb is primarily hosted within a 30-kilometre mineralized sequence. Platreef is contiguous with, and along strike from, Valterra Platinum's Mogalakwena PGM operations. Platreef hosts an underground deposit of platinum-group metals, nickel, copper, and gold mineralization, called the Flatreef deposit. The Flatreef is a thick, relatively flat-lying and high-grade orebody, which is amenable to highly mechanized, highly productive, underground bulk mining methods.
Since 2007, Flatreef has become one of the largest undeveloped precious metals deposits globally, with 56 million ounces in platinum equivalent Indicated Mineral Resources and 74 million ounces in platinum equivalent Inferred Mineral Resources, at a 2.0 g/t 3PE + AU cut-off. The Flatreef is also host to one of the world's largest undeveloped nickel sulphide mineral resources.
Phase 1 concentrator operations started in November 2025 with the first production of concentrate. Construction activities on the Phase 2 concentrator commenced during the following quarter in March 2026. The Phase 2 expansion is expected to complete in Q4 2027 and fully ramp up in Q4 2028.
Platreef summary of quarterly production data from Phase 1 commissioning
| Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | |
| Platreef Phase 1 concentrator | ||||
| Ore tonnes milled (DMT) | 99,391 | 37,296 | 27,512 | 25,543 |
| Feed grade of ore milled (g/t) | 2.30 | 2.19 | 2.78 | 2.64 |
| Recovery (%) | 62.40% | 59.00% | 57.00% | 45.00% |
| PGM production (3PE + Au ounces) | 4,552 | 1,538 | 1,428 | 965 |
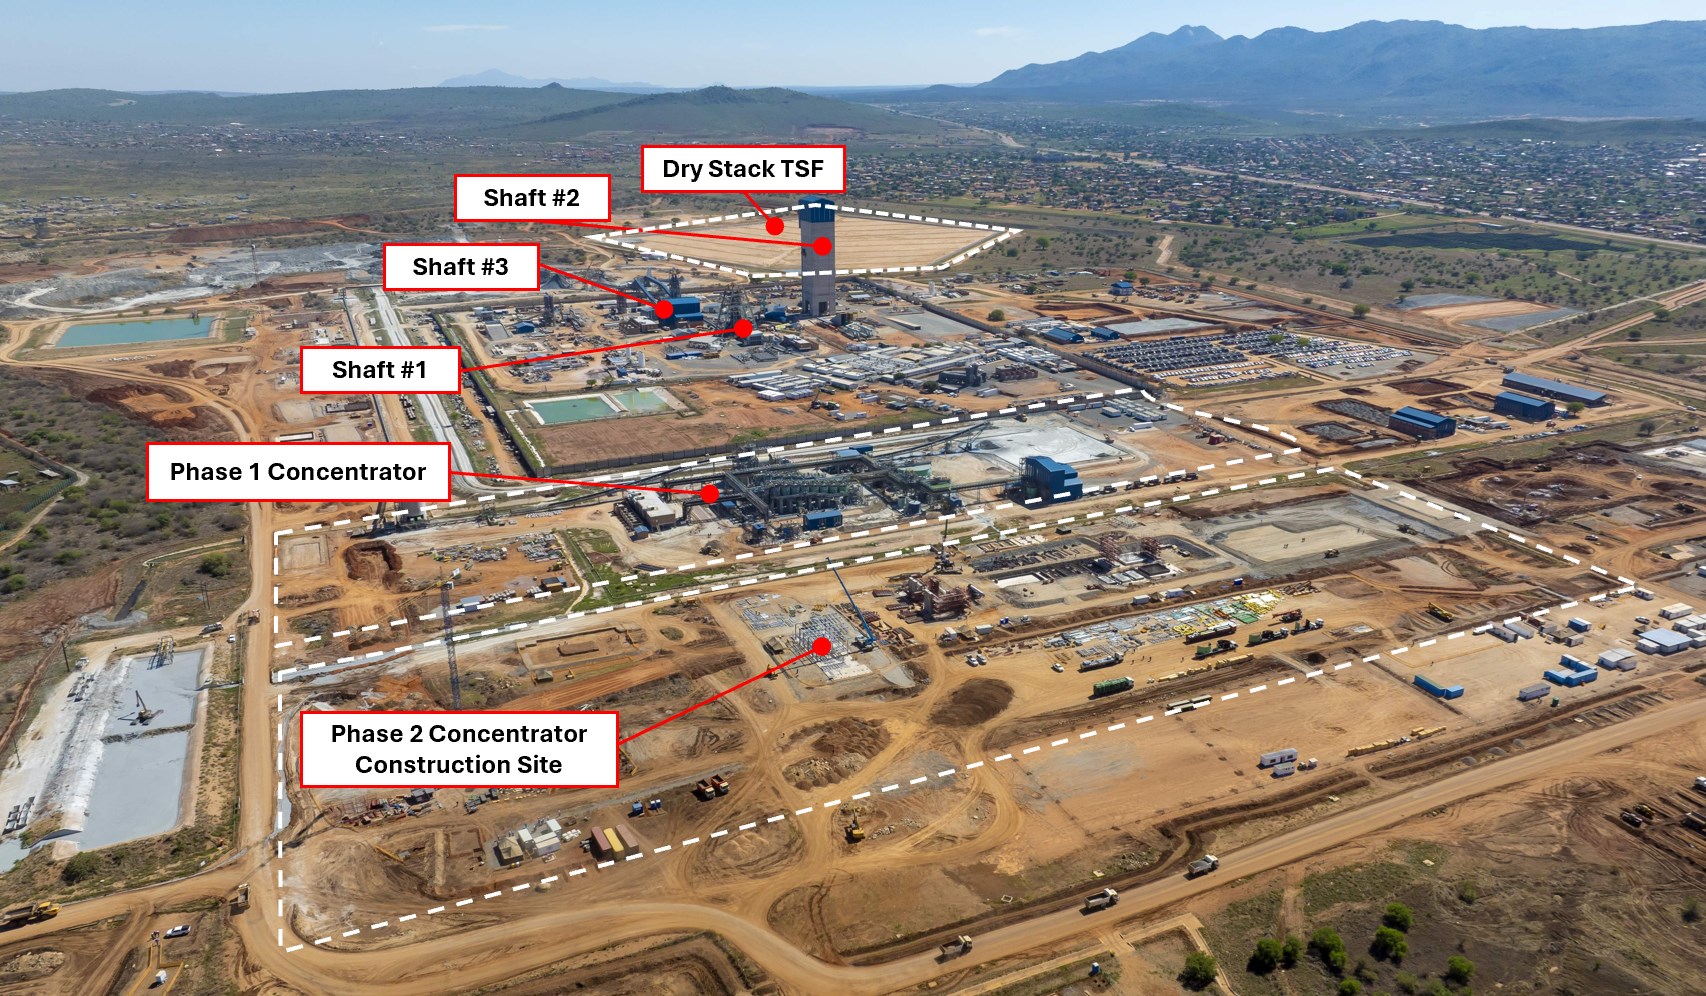
Aerial view over the Platreef Mine site, showing the Phase 2 concentrator construction site and adjacent Phase 1 concentrator in the foreground, with the shaft infrastructure in the background.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_bbd1221624ca7948_027full.jpg
Shaft #3 expands hoisting capacity at the Platreef Mine, unlocking Phase 1 operations while supporting underground development for Phase 2 expansion from Q4 2027
Production from the Platreef Mine's 0.8-Mtpa Phase 1 concentrator started on November 18, 2025. Since then, the mine has produced approximately 8,483 ounces of platinum, palladium, rhodium, and gold. Phase 1 operations have not yet reached commercial production. Therefore, production rates achieved to date do not reflect steady-state conditions.
Platreef Mine’s Phase 1 concentrator continued to be campaigned, or batch operated, during the quarter, fed by lower-grade development ore. Identified bottlenecks in the underground materials handling and tailings filtration systems have largely been resolved, with mining and milling rates expected improve further in the fourth quarter. The stoping (production mining) of higher-grade stopes is also expected to ramp up in Q4 2026.
Construction of Shaft #3 was completed on schedule in late Q1 2026, with the first ore hoisted to the surface on April 1, 2026. Commissioning of the shaft was finalized in June. Commissioning of the underground infrastructure supporting Shaft #3, consisting of a crusher, two conveyor belts and two strike tips, was also completed in June 2026.
Following the commissioning of Shaft #3 and its associated underground infrastructure, the total hoisting capacity at the Platreef Mine has increased significantly. The new shaft also enables the concurrent hoisting of stoping ore and development waste, which was previously not possible with Shaft #1.
Following the increase in hoisting capacity, stoping (production mining) of the higher-grade ore within the Flatreef orebody commenced at the end of the second quarter. The mining of two stopes has been completed so far. Mining rates are expected to ramp up throughout the remainder of Q4 2026.
Shaft #3 is now also hoisting development waste, as the underground infrastructure is constructed in preparation for the Phase 2 expansion, which is expected to be completed by the end of 2027.
Construction of Phase 2 concentrator advancing on schedule
Earthworks on the Phase 2 expansion's 3.3-million-tonne-per-annum concentrator began at the start of Q2 2026 and continue to advance on schedule for completion by the end of 2027. Civil works and engineering works on the concentrator are advancing to plan. The procurement of mechanical and electrical secondary long-lead items is complete, as well as the placing of the electrical, control, and instrumentation (EC&I) packages. The Structural, Mechanical, Piping, and Platework (SMPP) installation package for the Phase 2 flotation plant has also been placed.
Earthworks on the Phase 2 expansion's dry-stacked tailings storage facility (TSF) also commenced during Q3 2026, with completion expected in Q4 2027.
The widening of Shaft #2 from its current diameter of 3.1 metres to 10 metres, which commenced at the start of the second quarter, is progressing as planned. The work consists of a mining technique called slipe-and-line that widens the shaft from the top down, while simultaneously installing a permanent shaft-wall lining. Shaft equipping is expected to commence in Q1 2028.
Shaft #2 is expected to be ready to hoist labour and materials by the end of 2028 and ready to hoist ore by the end of 2029, supporting both the steady-state operations of Phase 2, as well as the future Phase 3 expansion.
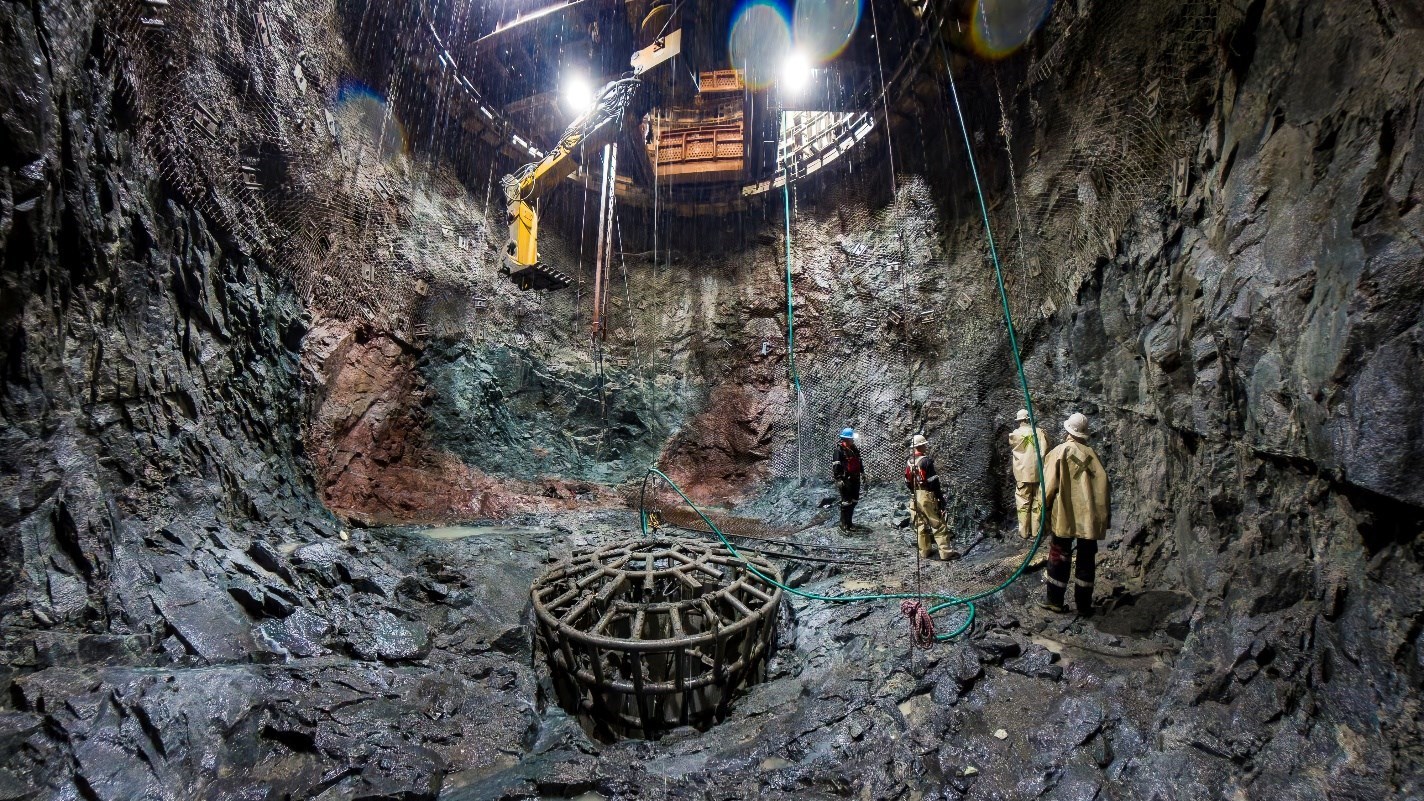
View from inside Shaft #2. The widening of the shaft consists of blasting 3.0-metre benches from the top of the shaft down. Waste rock from the blast is dropped down the existing 3.1-metre shaft (shown in the centre of the picture) using a robotic arm suspended from a platform (top of picture). Once complete, Shaft #2 will be the largest shaft in Africa.
To view an enhanced version of this graphic, please visit:
https://images.newsfilecorp.com/files/3396/322386_bbd1221624ca7948_028full.jpg
4. Global Exploration Portfolio
Ivanhoe's group 2026 exploration budget was upsized in early Q2 2026 to $126 million from $90 million. The 2026 budget is now more than double the group's 2025 exploration expenditure of $60 million, as confidence continues to grow across the company's exploration portfolio, most notably in the Western Forelands.
The total group exploration budget is allocated as follows: $86 million to the Western Forelands Exploration Project in the DRC, $20 million to the company's joint venture in Kazakhstan, and the remaining $20 million to Ivanhoe's exploration activities in Angola, Zambia and South Africa.
Western Forelands Exploration Project, DRC
54%- to 100%-owned by Ivanhoe Mines
The Western Forelands Exploration Project consists of a licence package covering 2,427 square kilometres (km2) adjacent to the Kamoa-Kakula Copper Complex in the Democratic Republic of the Congo (DRC). The area of the Western Forelands licence package is approximately six times larger than that of the Kamoa-Kakula Copper Complex.
An updated Mineral Resource Estimate (MRE) for the Makoko District including Makoko, Makoko West and Kitoko, was released on September 8, 2026. The Makoko District discovery now ranks as the world's largest and highest-grade copper discovery of the past decade.
In the 15 months between the 2025 Mineral Resource and the 2026 Mineral Resource update, approximately 64,000 metres of diamond drilling were completed across 106 holes. This drilling added approximately 0.13 million tonnes of contained copper in the Indicated Mineral Resource category for an increase of 17%. A further 2.63 million tonnes of contained copper have been added to the Inferred category for an increase of 31%.
Makoko District's Mineral Resources are now 34 million tonnes of ore at 2.66% copper for a total of 0.9 million tonnes of contained copper in the Indicated category, plus 612 million tonnes of ore at 1.80% copper for a total of 11.0 million tonnes of contained copper in the Inferred category.
The Western Forelands 2026 drilling program is on track to be Ivanhoe's largest to date, with more than 80,000 metres of diamond core and 16,000 metres of reverse circulation (RC) drilling planned. The diamond drilling program primarily focuses on step-out and infill drilling across the Makoko District. In addition, a 16,000-metre RC drilling program is planned for the Kamilli regional target area during the dry season.
Third quarter work focused on updating the Makoko District mineral resource estimate. Primary activities included resource expansion and infill drilling, geotechnical investigations, geophysics, and advancing early project development activities. Approximately 18,500 metres of diamond drilling were completed across 47 drill holes during Q3 2026, totalling 62,961 metres of diamond drilling completed year to date.
Ivanhoe's geologists believe that there is potential for further footprint expansion of the Makoko District, however, given the size of the discovery delineated to date and with the majority of the contained copper in Mineral Resources in the Inferred Category, drilling going forward will be primarily focussed on in-filling. The aim is to upgrade the shallow mineralization that has open-pit potential from the Inferred to the Indicated category.
In September, drilling started on the shallow infill program, with 25 holes planned, totalling 5,221 metres across as a 200- by 200-metre grid, to a maximum depth of 200 metres below surface.
Project development workstreams advanced significantly in the third quarter at Makoko, with several workstreams transitioning from planning to field implementation. Community resettlement & livelihood restoration programs advanced with a relocation site selected. Early works also progressed, with sterilization drilling, perimeter road construction, camp infrastructure early works. Completion of the camp is targeted by Q2 2027.
A dedicated diamond drill rig continued geotechnical drilling throughout the quarter. Six geotechnical holes were completed in July, four in August and three in September.
Since November 2025, a total of 11 geotechnical holes have been completed across the Makoko District.
North-Western Province, Zambia
100%-owned by Ivanhoe Mines
Ivanhoe's geologists believe that the Central African Copperbelt extends further west from the Western Forelands basin into western Zambia and eastern Angola.
Ivanhoe Mines was awarded a 7,757-square-kilometre (km²) exploration licence package, located in a highly strategic area of Zambia's North-Western Province in early Q2 2025. The 100%-owned landholding is over three times larger than Ivanhoe's Western Forelands Exploration Project and is situated between the company's existing DRC assets and the Angolan exploration licences. Ivanhoe's significantly underexplored licence package in Zambia has the potential to unlock the next generation of copper discoveries.
Initial exploration activities in 2025 were focused on analyzing historical geophysical and geological data from the licence's previous owners, as well as conducting an airborne gravity gradiometer (AGG) and magnetics survey. Data analysis from the surveys has generated several target areas across the licence for follow-up drilling.
During the quarter, diamond drilling targeting Falcon AGG magnetic and gravity anomalies continued on the targets. Drilling to date has confirmed the iron ore-copper-gold (IOCG) mineral system hypothesis. Several holes have encountered encouraging intersections of trace to weak chalcopyrite across intervals of 100 to 150m at depths from 70 to 120m depth below surface. These holes have been sampled and results are pending.
By quarter-end, preliminary drill testing of priority geophysical targets was progressing well against planned meterage of 9,000m, with three water bores and eight diamond drill holes completed for a cumulative 5,961 metres.
An aircore drilling program is being planned on a 1km x 1km grid to drill through Kalahari sand cover of 50 to 80m thick, and to carry out a top-of-regolith geochemical sampling program as follow-up across the target in Q4 2026.
Geophysical activities, including downhole wireline logging, hyperspectral core scanning and preparations for an AMT/MT geophysical survey, are also advancing well.
Moxico and Cuando Cubango Provinces, Angola
100%-owned by Ivanhoe Mines
Ivanhoe Mines is leveraging its proven exploration expertise from the Western Forelands and Kamoa-Kakula to unlock a major new frontier in Angola. The company has secured approximately 22,000 km² of highly prospective exploration licences in the Moxico and Cuando Cubango provinces, one of the largest greenfield sediment-hosted copper exploration packages in the region.
Following the signing of a mining investment contract with Angola's National Agency for Mineral Resources on November 27, 2023, with limited to no prior exploration to date, exploration activities commenced with airborne magnetic and airborne gravity geophysical mapping of the full 22,000 km2 licence package in June 2024. Ivanhoe's exploration team then commenced a 600-km² baseline soil geochemical sampling. Other field work completed since consists of ground-based geophysical work, including Audio-frequency Magnetotellurics (AMT), Magnetotellurics (MT), and Passive Seismic surveys.
A 12-hole stratigraphic drill program was started in late 2025 and paused after one drill hole was completed due to the onset of the wet season. Drilling restarted in the second quarter, with only three diamond drill holes having been completed to date due to poor contractor performance. Q3 2026 activities mostly focused on advancing regional geological understanding, preparing for an expanded drilling program and progressing licence, infrastructure and community initiatives. The drill program will restart following the mobilization of a new contractor at the end of the wet season in 2027.
The Chu-Sarysu Basin Exploration Joint Venture, Central Kazakhstan
20%-owned by Ivanhoe Mines (option to acquire up to 80%)
Ivanhoe Mines has established a strategic exploration joint venture with UK-based Pallas Resources to unlock the potential of the Chu-Sarysu Copper Basin in Kazakhstan. The basin is recognized as the world's third-largest sediment-hosted copper district. The partnership covers a vast and highly prospective 16,708 km² licence area, enriched by a comprehensive archive of Soviet-era exploration data.
Under the agreement announced on February 12, 2025, Ivanhoe has committed to $18.7 million in exploration funding over an initial two-year period, with the option to increase its ownership stake to 80% through staged earn-in milestones.
The initial $18.7 million investment has been fully drawn down for the initial geophysical and diamond-drilling program, which began in Q3 2025. From May 2026, an additional $20 million was invested in the joint venture, more than doubling the planned drill program to approximately 40,000 metres. The additional budget will be allocated across all licences, thereby increasing Ivanhoe’s earn-in across them all.
Ongoing regional and prospect-scale geophysical and geochemical surveys, as well as stratigraphic drilling completed to date, continues to show significant promise across the underexplored, high-potential copper district. A total of 6 diamond drill rigs and 2 KGK rigs were operational at the end of Q3, which have completed 17,528 metres of drilling year to date.
One drill hole intersected more than 250 metres (from 671 metres depth) of altered mudstone-argillite, containing trace to weak chalcopyrite mineralization and localized bornite associated with calcite veining. The mineralized interval consists of repetitive bleached sedimentary packages interlayered with hematitic red-bed sequences. This hole represents the most significant sediment-hosted, hydrothermal copper system intersected to date within the program.
SELECTED QUARTERLY FINANCIAL INFORMATION
The following table summarizes selected financial information for the prior eight quarters. Revenue from commercial production at the Kipushi Mine commenced in Q4 2024. Also included in revenue for the company, is revenue from pre-production sales at the Platreef Mine which commenced in Q4 2025. All revenue from production at Kamoa-Kakula is recognized within the Kamoa Holding joint venture. Ivanhoe did not declare or pay any dividend or distribution in any financial reporting period.
| Three months ended | ||||
| September 30, | June 30, | March 31, | December 31, | |
| 2026 | 2026 | 2026 | 2025 | |
| $'000 | $'000 | $'000 | $'000 | |
| Revenue | 263,836 | 152,611 | 165,529 | 138,435 |
| Cost of sales | (186,674) | (108,058) | (132,537) | (120,518) |
| Finance income | 46,739 | 44,990 | 43,895 | 45,099 |
| Share of profit (loss) from joint venture | 25,251 | 16,277 | (42,040) | 45,647 |
| General and administrative expenditure | (17,026) | (15,546) | (19,428) | 4,518 |
| Exploration and project evaluation expenditure | (43,940) | (15,226) | (15,951) | (19,722) |
| Deferred tax recovery (expense) | (19,555) | 4,261 | 3,157 | (32,995) |
| Finance costs | (5,832) | (4,632) | (4,132) | (9,314) |
| Share-based payments | (6,212) | (4,166) | (2,604) | (5,324) |
| (Loss) gain on fair valuation of derivative liability | (17,638) | (17,153) | 7,261 | (3,125) |
| Profit (loss) attributable to: | ||||
| Owners of the company | 50,641 | 49,741 | 17 | 54,687 |
| Non-controlling interests | (5,822) | (3,487) | (2,045) | (14,774) |
| Total comprehensive income (loss) attributable to: | ||||
| Owners of the company | 45,665 | 96,769 | (29,917) | 83,544 |
| Non-controlling interest | (6,336) | 1,339 | (5,095) | (11,687) |
| Basic profit per share | 0.04 | 0.03 | 0.00 | 0.04 |
| Diluted profit per share | 0.04 | 0.03 | 0.00 | 0.04 |
| Three months ended | ||||
| September 30, | June 30, | March 31, | December 31, | |
| 2025 | 2025 | 2025 | 2024 | |
| $'000 | $'000 | $'000 | $'000 | |
| Revenue | 129,403 | 96,757 | 77,020 | 40,818 |
| Cost of sales | (122,151) | (100,217) | (81,771) | (51,563) |
| Share of profit from joint venture | 11,305 | 15,704 | 107,948 | 73,620 |
| Finance income | 43,855 | 43,583 | 41,623 | 56,041 |
| General and administrative expenditure | (2,068) | (10,378) | (9,957) | (19,633) |
| Exploration and project evaluation expenditure | (10,324) | (8,585) | (9,145) | (15,845) |
| Finance costs | (20,920) | (4,947) | (7,838) | (6,849) |
| Deferred tax recovery | 3,169 | 7,842 | 4,374 | 12,663 |
| Share-based payments | (6,194) | (4,447) | (2,418) | (2,977) |
| Profit (loss) attributable to: | ||||
| Owners of the company | 33,057 | 44,051 | 129,760 | 99,344 |
| Non-controlling interests | (2,505) | (8,726) | (7,560) | (11,338) |
| Total comprehensive income (loss) attributable to: | ||||
| Owners of the company | 55,839 | 60,900 | 135,033 | 60,964 |
| Non-controlling interest | (3) | (7,066) | (7,161) | (15,158) |
| Basic profit per share | 0.02 | 0.03 | 0.10 | 0.07 |
| Diluted profit per share | 0.02 | 0.03 | 0.10 | 0.07 |
DISCUSSION OF RESULTS OF OPERATIONS
Review of Ivanhoe Mines for the three months ended September 30, 2026 vs. September 30, 2025
The company's revenue was $264 million for the third quarter of 2026, $135 million higher than the same period in 2025 ($129 million). Of the total revenue recognized for the quarter, $255 million was from zinc concentrate sales at the Kipushi Mine, while $5 million was attributable to pre-commercial production revenue at the Platreef Mine. Cost of sales for the three months ended September 30, 2026 was $187 million, up from $122 million for the same period in 2025, with cost of sales for the quarter mainly due to the Kipushi Mine ($175 million). Results for the Kipushi Mine is explained separately in the "Review of the Kipushi Mine" section below.
The company's share of profit from the Kamoa Holding joint venture was $14 million more in Q3 2026 compared to the same period in 2025 and is explained separately in the "Review of the Kamoa-Kakula Copper Complex" section below.
Ivanhoe's exploration and project evaluation expenditure amounted to $44 million in Q3 2026 and $10 million for the same period in 2025. Of the total exploration and project evaluation expenditure for Q3 2026, $35 million related to the company's Western Forelands exploration licences, $6 million related to the company's Kazakhstan exploration, and the remainder related mainly to Ivanhoe's Zambian and Angolan exploration.
Exploration and project evaluation expenditure at the Western Forelands Exploration Project increased by $27 million from $8 million for the three months ended September 30, 2025 to $35 million for the same period in 2026, mainly due to $16 million spent on compensation to project-affected persons associated with the relocation and resettlement process at the Makoko District.
Finance income for Q3 2026 amounted to $47 million and was $3 million more than for the same period in 2025 ($44 million). Included in finance income is the interest earned on loans to the Kamoa Holding joint venture which amounted to $41 million for Q3 2026, and $36 million for the same period in 2025 and increased due to the higher accumulated loan balance.
Included in the profit for the three months ended September 30, 2026, is a loss on the fair valuation of derivative liabilities of $18 million. The derivative liabilities arise on zinc and copper hedging contracts undertaken by the company. Of the $18 million loss incurred, $5 million related to zinc and copper hedging contracts that realized during the period, while $13 million related to zinc and copper hedging contracts that were unrealized at the end of the period.
The company recorded a profit of $45 million and a total comprehensive income of $39 million for Q3 2026, compared to a profit of $31 million and a total comprehensive income of $56 million for the same period in 2025.
The total comprehensive income for the three months ended September 30, 2026, included an exchange loss on translation of foreign operations of $5 million, compared to an exchange gain of $25 million for the same period in 2025, resulting mainly from the weakening of the South African Rand during the period.
Review of the Kipushi Mine for the three months ended September 30, 2026 vs. September 30, 2025
The company sold 69,384 tonnes of payable zinc produced by the Kipushi Mine in the third quarter of 2026, realizing revenue of $255 million at a cost of sales of $175 million. This is compared to 49,744 tonnes of payable zinc sold for the same period in 2025, realizing revenue of $129 million at a cost of sales of $122 million. Kipushi's cost of sales per pound of payable zinc sold was $1.14/lb. for the third quarter of 2026 and was $1.11/lb. in Q3 2025. Cash cost (C1) per pound of payable zinc sold in the third quarter of 2026 averaged $0.91/lb. compared with $0.95/lb. for the same period in 2025. Kipushi's segmented profit for the third quarter of 2026 was $47 million (Q3 2025: $8 million) and EBITDA was $108 million (Q3 2025: $27 million).
Revenue includes the mark-to-market gain impact of remeasurement of contract receivables of $12 million for the three months ended September 30, 2026. The realized, provisional, and forward zinc prices used for the remeasurement (mark-to-market) of contract receivables of Kipushi for the three months ended September 30, 2026, and for the same period in 2025, can be summarized as follows:
| Three months ended | ||
| September 30, | ||
| 2026 | 2025 | |
| Realized during the period - open at the start of the period | ||
| Opening forward price ($/lb.)(1) | 1.58 | 1.26 |
| Realized price ($/lb.)(1) | 1.66 | 1.25 |
| Payable zinc tonnes sold | 24,920 | 25,986 |
| Remeasurement of contract receivables ($'000) | 4,303 | (864) |
| Realized during the period - new zinc sold in the current period | ||
| Provisional price ($/lb.)(1) | 1.66 | 1.27 |
| Realized price ($/lb.)(1) | 1.80 | 1.30 |
| Payable zinc tonnes sold | 22,217 | 20,281 |
| Remeasurement of contract receivables ($'000) | 6,624 | 1,466 |
| Open at the end of the period - new zinc sold in the current period | ||
| Provisional price ($/lb.)(1) | 1.77 | 1.31 |
| Closing forward price ($/lb.)(1) | 1.78 | 1.34 |
| Payable zinc tonnes sold | 47,167 | 29,464 |
| Remeasurement of contract receivables ($'000) | 1,139 | 1,946 |
| Total remeasurement of contract receivables ($'000) | 12,066 | 2,548 |
(1) Calculated on a weighted average basis
Review of the Kamoa-Kakula Copper Complex for the three months ended September 30, 2026 vs. September 30, 2025
The company recognized income in aggregate of $67 million from the joint venture in Q3 2026 and $47 million for the same period in 2025, which can be summarized as follows:
| Three months ended | ||
| September 30, | ||
| 2026 | 2025 | |
| $'000 | $'000 | |
| Company's share of profit from joint venture | 25,251 | 11,305 |
| Interest on loan to joint venture | 41,385 | 35,905 |
| Company's income recognized from joint venture | 66,636 | 47,210 |
The company's share of profit from the Kamoa Holding joint venture was $14 million more in Q3 2026 compared to the same period in 2025 and is broken down in the following table:
| Three months ended | ||
| September 30, | ||
| 2026 | 2025 | |
| $'000 | $'000 | |
| Revenue from contract receivables | 1,013,208 | 555,293 |
| Remeasurement of contract receivables | 20,779 | 11,072 |
| Revenue | 1,033,987 | 566,365 |
| Cost of sales | (678,297) | (438,230) |
| Gross profit | 355,690 | 128,135 |
| General and administrative costs | (63,422) | (54,966) |
| Amortization of mineral property | (4,688) | (4,584) |
| Profit from operations | 287,580 | 68,585 |
| Finance costs | (145,792) | (110,781) |
| Foreign exchange (loss) gain | (7,980) | 70,113 |
| Finance income and other | 6,071 | 5,926 |
| Profit before taxes | 139,879 | 33,843 |
| Current tax (expense) recovery | (59,842) | 47,648 |
| Deferred tax expense | (21,770) | (55,469) |
| Profit after taxes | 58,267 | 26,022 |
| Non-controlling interest of Kamoa Holding | (7,256) | (3,184) |
| Total comprehensive income for the period attributable to the owners of the joint venture | 51,011 | 22,838 |
| Company's share of profit from joint venture (49.5%) | 25,251 | 11,305 |
The Kamoa-Kakula Copper Complex sold 67,025 tonnes of payable copper in Q3 2026 realizing revenue of $1.03 billion for the Kamoa Holding joint venture, compared to 61,528 tonnes of payable copper sold for revenue of $566 million for the same period in 2025. Of the $1.03 billion of revenue recognized by Kamoa-Kakula during the three months ended September 30, 2026, $100 million relates to the sale of 109,240 tonnes of sulphuric acid. Revenue was boosted by higher copper prices in 2026, with the provisional price of $6.41/lb. and a realized price of $6.12/lb. for Q3 2026, compared to a provisional price of $4.44/lb and a realized price of $4.42/lb. for Q3 2025.
Kamoa-Kakula's cost of sales per pound of payable copper sold was $4.59/lb. for the third quarter of 2026 and was $3.23/lb. in Q3 2025. Cash cost (C1) per pound of payable copper sold in the third quarter of 2026 averaged $3.00/lb. compared with $2.62/lb. for the same period in 2025, with the increase mainly attributable to increased mining and smelting costs which were partially offset by sulphuric acid credits.
The realized, provisional and forward copper prices used for the remeasurement (mark-to-market) of contract receivables for the three months ended September 30, 2026, and for the same period in 2025, can be summarized as follows:
| Three months ended | ||
| September 30, | ||
| 2026 | 2025 | |
| Realized during the period - open at the start of the period | ||
| Opening forward price ($/lb.)(1) | 6.02 | 4.50 |
| Realized price ($/lb.)(1) | 6.11 | 4.40 |
| Payable copper tonnes sold | 21,406 | 27,067 |
| Remeasurement of contract receivables ($'000) | 4,414 | (5,850) |
| Realized during the period - new copper sold in the current period | ||
| Provisional price ($/lb.)(1) | 6.13 | 4.41 |
| Realized price ($/lb.)(1) | 6.16 | 4.44 |
| Payable copper tonnes sold | 5,067 | 43,340 |
| Remeasurement of contract receivables ($'000) | 310 | 2,529 |
| Open at the end of the period - open at the start of the period | ||
| Opening forward price ($/lb.)(1) | - | 4.48 |
| Closing forward price ($/lb.)(1) | - | 4.72 |
| Payable copper tonnes sold | - | 11,126 |
| Remeasurement of contract receivables ($'000) | - | 5,877 |
| Open at the end of the period - new copper sold in current period | ||
| Provisional price ($/lb.)(1) | 6.44 | 4.51 |
| Closing forward price ($/lb.)(1) | 6.55 | 4.72 |
| Payable copper tonnes sold | 61,958 | 18,188 |
| Remeasurement of contract receivables ($'000) | 16,055 | 8,516 |
| Total remeasurement of contract receivables ($'000) | 20,779 | 11,072 |
(1) Calculated on a weighted average basis
The finance costs recognized in the Kamoa Holding joint venture increased by $35 million from $111 million for the three months ended September 30, 2025 to $146 million for the same period in 2026, with the increase largely attributable to the interest on shareholder loans, which increased due to the higher accumulated loan balances, the interest on bank loans and overdraft facilities and a decrease in borrowing costs capitalized as qualifying assets reached completion. The finance costs can be broken down as follows:
| Three months ended | ||
| September 30, | ||
| 2026 | 2025 | |
| $'000 | $'000 | |
| Interest on shareholder loans | 83,567 | 72,501 |
| Interest on provisional and advance payment facilities | 28,876 | 35,363 |
| Interest on bank loans and overdraft facilities | 20,805 | 8,637 |
| Interest on syndicated loans | 8,823 | 11,508 |
| Lease liability unwinding | 6,473 | 1,670 |
| Rehabilitation unwinding | 6,913 | 1,411 |
| Interest on equipment financing facilities | 610 | 1,446 |
| Interest capitalized as borrowing costs | (10,275) | (21,755) |
| 145,792 | 110,781 | |
Review of Ivanhoe Mines for the nine months ended September 30, 2026 vs. September 30, 2025
The company's revenue was $582 million for the nine months ended September 30, 2026 and was $279 million more than for the same period in 2025 ($303 million). Of the total revenue recognized for the nine months ended September 30, 2026, $562 million was from the Kipushi Mine, while $12 million was attributable to pre-commercial production revenue at the Platreef Mine. Cost of sales for the nine months ended September 30, 2026 was $427 million, and was $304 million for the same period in 2025, with cost of sales for the period mainly attributable to the Kipushi Mine ($405 million). Results for the Kipushi Mine is explained separately in the "Review of the Kipushi Mine" section below.
The company recorded its share of loss from the Kamoa Holding joint venture of $1 million for the nine months ended September 30, 2026, compared to a profit of $135 million for the same period in 2025. The Kamoa Holding joint venture incurred a loss for the period as a result of a $183 million tax adjustment in settlement of tax claims related to tax audit assessments of Kamoa Copper in prior years during Q1 2026. Results for the Kamoa Holding joint venture is explained separately in the "Review of the Kamoa-Kakula Copper Complex" section below.
Ivanhoe's exploration and project evaluation expenditure amounted to $75 million for the nine months ended September 30, 2026, and $28 million for the same period in 2025. Of the total exploration and project evaluation expenditure for the nine months ended September 30, 2026, $54 million related to the company's Western Forelands exploration licences, $14 million related to the company's Kazakhstan exploration and the remainder related mainly to Ivanhoe's Zambian and Angolan exploration.
Exploration and project evaluation expenditure at the Western Forelands Exploration Project increased by $31 million from $23 million for the nine months ended September 30, 2025, to $54 million for the same period in 2026, mainly due to increased drilling, site establishment costs and relocation and resettlement costs incurred as exploration activity increased at the Makoko District.
Included in general and administrative expenses for the nine months ended September 30, 2026, is foreign exchange losses of $10 million compared with foreign exchange gains of $5 million for the same period in 2025.
Finance income amounted to $136 million for the nine months ended September 30, 2026, and $129 million for the same period in 2025. Included in finance income is the interest earned on loans to the Kamoa Holding joint venture to fund past development that amounted to $116 million for the nine months ended September 30, 2026, and $105 million for the same period in 2025 and increased due to the higher accumulated loan balance.
Included in the profit for the nine months ended September 30, 2026, is a loss on the fair valuation of derivative liabilities of $28 million. The derivative liabilities arise on zinc and copper hedging contracts undertaken by the company. Of the $28 million loss recognized, $7 million related to zinc and copper hedging contracts that realized during the period, while $21 million related to zinc and copper hedging contracts that were unrealized at the end of the period.
The company recorded a profit of $89 million and a total comprehensive income of $102 million for the nine months ended September 30, 2026, compared to a profit of $188 million and a total comprehensive income of $238 million for the same period in 2025.
Review of the Kipushi Mine for the nine months ended September 30, 2026 vs. September 30, 2025
The company sold 167,748 tonnes of payable zinc produced by the Kipushi Mine in the nine months ended September 30, 2026, realizing revenue of $562 million at a cost of sales of $405 million. This is compared to 123,200 tonnes of payable zinc sold for the same period in 2025, realizing revenue of $303 million at a cost of sales of $304 million. The cost of sales for the nine months ended September 30, 2026 also included depreciation and amortization of $64 million, which was $48 million for the same period in 2025. Cost of sales per pound of payable zinc sold was $1.09/lb. for the nine months ended September 30, 2026, compared to $1.12/lb. for the same period in 2025. Cash cost (C1) per pound of payable zinc sold for the nine months ended September 30, 2026 averaged $0.89/lb. and $0.95/lb. for the same period in 2025.
Kipushi's segmented profit and EBITDA were $91 million and $218 million respectively for the nine months ended September 30, 2026. This is compared with a segmented loss of $4 million and an EBITDA of $46 million for the same period in 2025.
The realized, provisional, and forward zinc prices used for the remeasurement (mark-to-market) of contract receivables of Kipushi for the nine months ended September 30, 2026, and for the same period in 2025, can be summarized as follows:
| Nine months ended | ||
| September 30, | ||
| 2026 | 2025 | |
| Realized during the period - open at the start of the period | ||
| Opening forward price ($/lb.)(1) | 1.41 | 1.34 |
| Realized price ($/lb.)(1) | 1.49 | 1.28 |
| Payable zinc tonnes sold | 32,966 | 11,596 |
| Remeasurement of contract receivables ($'000) | 5,835 | (1,606) |
| Realized during the period - new zinc sold in the current period | ||
| Provisional price ($/lb.)(1) | 1.55 | 1.24 |
| Realized price ($/lb.)(1) | 1.61 | 1.26 |
| Payable zinc tonnes sold | 120,581 | 93,736 |
| Remeasurement of contract receivables ($'000) | 15,365 | 3,397 |
| Open at the end of the period - new zinc sold in the current period | ||
| Provisional price ($/lb.)(1) | 1.77 | 1.31 |
| Closing forward price ($/lb.)(1) | 1.78 | 1.34 |
| Payable zinc tonnes sold | 47,167 | 29,464 |
| Remeasurement of contract receivables ($'000) | 1,139 | 1,946 |
| Total remeasurement of contract receivables ($'000) | 22,339 | 3,737 |
(1) Calculated on a weighted average basis
Review of the Kamoa-Kakula Copper Complex for the nine months ended September 30, 2026 vs. September 30, 2025
The company recognized income in aggregate of $116 million from the joint venture in the nine months ended September 30, 2026 (2025: $240 million), which can be summarized as follows:
| Nine months ended | ||
| September 30, | ||
| 2026 | 2025 | |
| $'000 | $'000 | |
| Company's share of (loss) profit from joint venture | (512) | 134,957 |
| Interest on loan to joint venture | 116,275 | 104,912 |
| Company's income recognized from joint venture | 115,763 | 239,869 |
The company recorded its share of loss from the Kamoa Holding joint venture of $1 million for the nine months ended September 30, 2026, compared to a profit of $135 million for the same period in 2025, the breakdown of which is summarized in the following table:
| Nine months ended | ||
| September 30, | ||
| 2026 | 2025 | |
| $'000 | $'000 | |
| Revenue from contract receivables | 2,733,374 | 2,346,550 |
| Remeasurement of contract receivables | 43,360 | 68,501 |
| Revenue | 2,776,734 | 2,415,051 |
| Cost of sales | (1,907,062) | (1,531,687) |
| Gross profit | 869,672 | 883,364 |
| General and administrative costs | (188,645) | (129,573) |
| Amortization of mineral property | (12,842) | (14,379) |
| Profit from operations | 668,185 | 739,412 |
| Foreign exchange (loss) gain | (11,626) | 53,372 |
| Finance income and other | 16,624 | 16,647 |
| Finance costs | (344,032) | (223,010) |
| Impairment | - | (68,202) |
| Profit before taxes | 329,151 | 518,219 |
| Current tax expense | (323,493) | (202,436) |
| Deferred tax (expense) recovery | (25,778) | 13,366 |
| (Loss) profit after taxes | (20,120) | 329,149 |
| Non-controlling interest of Kamoa Holding | 19,085 | (56,509) |
| Total comprehensive income (loss) for the period attributable to the owners of the joint venture | (1,035) | 272,640 |
| Company's share of (loss) profit from joint venture (49.5%) | (512) | 134,957 |
The Kamoa-Kakula Copper Complex sold 194,893 tonnes of payable copper in the nine months ended September 30, 2026, realizing revenue of $2.78 billion for the Kamoa Holding joint venture, compared to 273,205 tonnes of payable copper sold for revenue of $2.42 billion for the same period in 2025. The increase in the average provisional copper sales price achieved during the nine months ended September 30, 2026, contributed to the increase in revenue despite the decrease in payable copper sold when compared with the same period in 2025. Of the $2.78 billion of revenue recognized by Kamoa-Kakula during the nine months ended September 30, 2026, $209 million relates to the sale of 336,537 tonnes of sulphuric acid.
Revenue was boosted by higher copper prices in 2026, with the provisional price of $6.10/lb. and a realized price of $5.93/lb. for the nine months ended September 30, 2026, compared to a provisional price of $4.31/lb. and a realized price of $4.31/lb. for the same period in 2025.
Kamoa-Kakula's cost of sales per pound of payable copper sold was $4.44/lb. for the nine months ended September 30, 2026, and was $2.54/lb. for the same period in 2025. Cash cost (C1) per pound of payable copper sold averaged $2.80/lb. for the nine months ended September 30, 2025, compared with $1.97/lb. in 2025, with the increase mainly attributable to increased mining and smelting costs which were partially offset by sulphuric acid credits.
The realized and provisional copper prices used for the remeasurement (mark-to-market) of contract receivables for the nine months ended September 30, 2026, and for the same period in 2025, can be summarized as follows:
| Nine months ended | ||
| September 30, | ||
| 2026 | 2025 | |
| $'000 | $'000 | |
| Realized during the period - open at the start of the period | ||
| Opening forward price ($/lb.)(1) | 5.64 | 4.01 |
| Realized price ($/lb.)(1) | 5.81 | 4.14 |
| Payable copper tonnes sold | 50,249 | 79,985 |
| Remeasurement of contract receivables ($'000) | 18,565 | 21,811 |
| Realized during the period - new copper sold in the current period | ||
| Provisional price ($/lb.)(1) | 5.94 | 4.29 |
| Realized price ($/lb.)(1) | 5.97 | 4.36 |
| Payable copper tonnes sold | 132,935 | 243,891 |
| Remeasurement of contract receivables ($'000) | 8,740 | 32,914 |
| Open at the end of the period - new copper sold in current period | ||
| Provisional price ($/lb.)(1) | 6.44 | 4.51 |
| Closing forward price ($/lb.)(1) | 6.55 | 4.72 |
| Payable copper tonnes sold | 61,958 | 29,313 |
| Remeasurement of contract receivables ($'000) | 16,055 | 13,776 |
| Total remeasurement of contract receivables ($'000) | 43,360 | 68,501 |
(1) Calculated on a weighted average basis
The finance costs recognized in the Kamoa Holding joint venture was $223 million for the nine months ended September 30, 2025 and increased by $121 million to $344 million for the nine months ended September 30, 2026, largely due to the interest in shareholder loans, which increased due to the higher accumulated loan balance, the interest on bank loans and overdraft facilities and a decrease in borrowing costs capitalized as qualifying assets reached completion. The finance costs can be broken down as follows:
| Nine months ended | ||
| September 30, | ||
| 2026 | 2025 | |
| $'000 | $'000 | |
| Interest on shareholder loans | 234,787 | 211,839 |
| Interest on provisional and advance payment facilities | 81,884 | 110,696 |
| Interest on bank loans and overdraft facilities | 58,321 | 23,385 |
| Interest on syndicated loans | 30,059 | 34,126 |
| Rehabilitation unwinding | 10,145 | 4,423 |
| Lease liability unwinding | 9,543 | 5,105 |
| Interest on equipment financing facilities | 3,089 | 4,846 |
| Interest capitalized as borrowing costs | (83,797) | (171,410) |
| 344,031 | 223,010 | |
Financial position of Ivanhoe Mines as at September 30, 2026, vs. December 31, 2025
The company's total assets increased by $445 million, from $7,626 million as at December 31, 2025, to $8,071 million as at September 30, 2026. The increase in total assets was mainly attributable to the increase in property, plant and equipment of $395 million as project development continued at the Platreef Mine, the increase in the company's investment in the Kamoa Holding joint venture by $190 million and the increase in inventory by $47 million offset in part by the decrease in cash and cash equivalents and short term deposits by $242 million, as explained below.
Cash and cash equivalents and short-term deposits decreased by $242 million, from $885 million as at December 31, 2025, to $643 million as at September 30, 2026. The company spent $327 million on project development and acquiring other property, plant, and equipment and used $14 million in its operating activities. Of the total interest repaid during the nine months ended September 30, 2026, $59 million related to the semi-annual interest repayment on the Senior Notes, $8 million related to repayments of interest on the senior debt facility, $8 million related to repayments of interest on advance payment facilities, $4 million related to interest on overdraft facilities, $1 million related to fees on the unutilized revolving credit facility and $9 million related to interest on other term loan facilities. The company advanced equity contributions of $74 million to the Kamoa Holding joint venture during the nine months ended September 30, 2026.
Inventory increased by $47 million, from $66 million as at December 31, 2025, to $113 million as at September 30, 2026. Included in inventory is $53 million of zinc concentrate finished goods, up from $28 million at the end of 2025. Finished goods as at September 30, 2026 contains 41,923 tonnes of zinc in concentrate and increased from December 31, 2025 (28,345 tonnes) due to logistics constraints experienced during the second quarter of 2026. 32,680 tonnes of zinc in concentrate was en-route to the port at the end of Q3 2026 (December 31, 2025: 15,972 tonnes). The inventory balance as at September 30, 2026, also contains $26 million in ore stockpiles (December 31, 2025: $19 million). The ore stockpile contained approximately 257,629 tonnes of ore at an estimated average grade of 21.0% zinc (December 31, 2025: 303,038 tonnes of ore at an estimated average grade of 24.7% zinc).
The company's investment in the Kamoa Holding joint venture increased by $190 million from $3,571 million as at December 31, 2025, to $3,761 million as at September 30, 2026. The company's investment in the Kamoa Holding joint venture can be broken down as follows:
| September 30, | December 31, | |
| 2026 | 2025 | |
| $'000 | $'000 | |
| Company's share of net assets in joint venture | 2,360,639 | 2,286,901 |
| Loan advanced to joint venture | 1,399,964 | 1,283,689 |
| Total investment in joint venture | 3,760,603 | 3,570,590 |
The company's share of the net assets in the Kamoa Holding joint venture can be broken down as follows:
| September 30, 2026 | December 31, 2025 | |||
| 100% | 49.5% | 100% | 49.5% | |
| $'000 | $'000 | $'000 | $'000 | |
| Assets | ||||
| Property, plant and equipment | 7,492,149 | 3,708,614 | 7,085,455 | 3,507,300 |
| Indirect taxes receivable | 1,222,940 | 605,355 | 1,141,769 | 565,176 |
| Mineral property | 731,530 | 362,107 | 744,371 | 368,464 |
| Current inventory | 823,085 | 407,427 | 759,207 | 375,807 |
| Trade receivables | 565,660 | 280,002 | 336,094 | 166,367 |
| Long-term loan receivable | 452,942 | 224,206 | 428,363 | 212,040 |
| Right-of-use asset | 444,388 | 219,972 | 39,834 | 19,718 |
| Other receivables | 396,521 | 196,278 | 364,097 | 180,228 |
| Cash and cash equivalents | 354,306 | 175,381 | 310,590 | 153,742 |
| Run of mine stockpile | 12,086 | 5,982 | 104,790 | 51,871 |
| Prepaid expenses | 13,930 | 6,895 | 18,484 | 9,150 |
| Non-current deposits | 3,127 | 1,548 | 3,127 | 1,548 |
| Income taxes receivable | 17,593 | 8,709 | 88,289 | 43,703 |
| Deferred tax asset | - | - | 30,201 | 14,949 |
| Liabilities | ||||
| Shareholder loans | (2,828,374) | (1,400,045) | (2,593,586) | (1,283,825) |
| Term loan facilities | (1,282,145) | (634,662) | (1,069,004) | (529,157) |
| Advance payment facilities | (901,233) | (446,110) | (906,915) | (448,923) |
| Trade and other payables | (729,767) | (361,235) | (675,358) | (334,302) |
| Lease liability | (435,748) | (215,695) | (44,075) | (21,817) |
| Deferred tax liability | (365,423) | (180,884) | (369,851) | (183,076) |
| Overdraft facility | (354,584) | (175,519) | (276,430) | (136,833) |
| Rehabilitation provision | (152,993) | (75,732) | (132,004) | (65,342) |
| Dividends payable | 1,569 | 777 | (87,242) | (43,185) |
| Other provisions | (87,810) | (43,466) | (34,806) | (17,229) |
| Provisional payment facilities | (79,175) | (39,192) | (80,756) | (39,974) |
| Non-controlling interest | (545,607) | (270,075) | (564,641) | (279,497) |
| Net assets of the joint venture | 4,768,967 | 2,360,639 | 4,620,003 | 2,286,901 |
Before commencing commercial production in July 2021, the Kamoa Holding joint venture principally used loans from its shareholders to develop the Kamoa-Kakula Copper Complex through investing in development costs and other property, plant, and equipment.
Advance payment facilities represent financing arrangements linked to Kamoa-Kakula's offtake agreements with its customers. Each customer has provided advance payment facilities which are repaid by offsetting amounts payable in terms of provisional invoices in accordance with the terms of each agreement.
The repayments of the advanced payment facilities of the Kamoa Holding joint venture can be summarized as follows:
| More than | |||||
| 0-3 months | 3-6 months | 6-12 months | 12-24 months | 24 months | |
| $'000 | $'000 | $'000 | $'000 | $'000 | |
| As at September 30, 2026 | 31,818 | 33,000 | 266,000 | 553,848 | 16,567 |
Overdraft facilities represent drawn unsecured financing facilities from DRC financial institutions at an attractive cost of capital, utilized to augment cash generated from operations for Kamoa-Kakula's continued expansion and working capital. Total current overdraft facilities amount to $355 million, with an interest rate of approximately 6.5%.
The term loan facilities of the Kamoa Holding joint venture, incur interest at a weighted average rate of 8.76% per annum and can be summarized as follows:
| Description | Repayment terms | Maturity date | September 30, | December 31, |
| 2026 | 2025 | |||
| $'000 | $'000 | |||
| Syndicated term facility | Repayable in eight equal quarterly instalments starting from September 30, 2028 | Jun-30 | 585,435 | 398,868 |
| Offshore Term facility | Interest is paid quarterly & four quarterly payments of the principal amount starting on 31 December 2028 and 80% of the principal on maturity. | Sep-31 | 359,227 | 370,221 |
| Standard Bank facility agreement | Full repayment on July 2027 with extension option. | Jun-27 | 196,659 | 198,870 |
| United Bank for Africa loan facility | Interest is paid bi-annually & the principal is repaid on maturity. | Nov-27 | 100,422 | 50,472 |
| TMB facility | Quarterly payments for both the principal and interest amounts. | Jan-27 | 20,213 | - |
| Equipment financing facilities | Instalments on each quarterly facility repayment date | Mar-28 | 17,110 | 34,951 |
| Bank of Africa facility | Repayable in monthly instalments | Nov-27 | 3,079 | 15,623 |
| Total term loan facilities | 1,282,145 | 1,069,004 |
The repayments of the term loan facilities of the Kamoa Holding joint venture can be summarized as follows:
| More than | |||||
| 0-3 months | 3-6 months | 6-12 months | 12-24 months | 24 months | |
| $'000 | $'000 | $'000 | $'000 | $'000 | |
| As at September 30, 2026 | 229,321 | 146,034 | 441,301 | 134,755 | 330,734 |
The increase in Kamoa-Kakula's right-of-use asset and corresponding lease liability in 2026, represent the IFRS 16 accounting for the on-site hybrid solar facility with battery energy storage system (BESS). The contract with CrossBoundary Energy, the owner and operator of the facility was assessed against the requirements of IFRS 16, and it was concluded that the contract contained a lease.
The cash flows of the Kamoa Holding joint venture can be summarized as follows:
| Three months ended | Nine months ended | |||
| September 30, | September 30, | |||
| 2026 | 2025 | 2026 | 2025 | |
| $'000 | $'000 | $'000 | $'000 | |
| Net cash generated from (used in) operating activities before change in working capital items | 373,948 | (19,877) | 890,428 | 768,036 |
| Change in working capital items | (353,367) | 158,711 | (401,618) | (222,592) |
| Net cash used in investing activities | (180,465) | (354,804) | (781,010) | (918,573) |
| Net cash generated from financing activities | 384,093 | 93,541 | 337,382 | 397,412 |
| Effect of foreign exchange rates on cash | 616 | 568 | 920 | (349) |
| Net cash inflow (outflow) | 224,825 | (121,861) | 46,102 | 23,934 |
| Cash and cash equivalents - beginning of the period | 129,481 | 246,436 | 308,204 | 100,641 |
| Cash and cash equivalents - end of the period | 354,306 | 124,575 | 354,306 | 124,575 |
The Kamoa Holding joint venture's net increase in property, plant and equipment from December 31, 2025, to September 30, 2026, amounted to $407 million and can be further broken down as follows:
| Three months ended | Nine months ended | |||
| September 30, | September 30, | |||
| 2026 | 2025 | 2026 | 2025 | |
| $'000 | $'000 | $'000 | $'000 | |
| Kamoa Holding joint venture | ||||
| Expansion capital | 66,720 | 230,546 | 413,348 | 630,440 |
| Sustaining capital | 138,851 | 108,580 | 383,530 | 279,855 |
| 205,571 | 339,126 | 796,878 | 910,295 | |
| Depreciation capitalized | 20,622 | 14,321 | 56,445 | 44,786 |
| Total capital expenditure | 226,193 | 353,447 | 853,323 | 955,081 |
| Borrowing costs capitalized | 10,275 | 21,755 | 83,797 | 171,410 |
| Total additions to property, plant, and equipment for Kamoa Holding | 236,468 | 375,202 | 937,120 | 1,126,491 |
| Less depreciation, impairment, disposals, and foreign exchange translation | (230,517) | (163,459) | (530,426) | (479,099) |
| Net increase in property, plant, and equipment of Kamoa Holding | 5,951 | 211,743 | 406,694 | 647,392 |
The net increase in Ivanhoe's property, plant, and equipment amounted to $395 million, with additions of $337 million to project development and other property, plant, and equipment. Of this total, $286 million pertained to development costs and other acquisitions of property, plant and equipment at the Platreef Mine, while $48 million pertained to acquisitions of property, plant, and equipment at the Kipushi Mine.
The main components of the additions to property, plant and equipment - including capitalized development costs - at the Platreef Mine for the nine months ended September 30, 2026, and for the same period in 2025, are set out in the following tables:
| Three months ended | Nine months ended | |||
| September 30, | September 30, | |||
| 2026 | 2025 | 2026 | 2025 | |
| $'000 | $'000 | $'000 | $'000 | |
| Platreef Mine | ||||
| Phase 2 construction | 78,991 | 29,283 | 159,445 | 77,659 |
| Site costs | 11,098 | 15,681 | 42,675 | 38,245 |
| Salaries and benefits | 18,493 | 9,215 | 43,362 | 27,737 |
| Administrative and other expenditure | 14,497 | 4,409 | 25,241 | 11,731 |
| Depreciation | 3,188 | 2,774 | 10,852 | 7,798 |
| Social and environmental | 949 | 899 | 3,427 | 2,807 |
| Phase 1 construction | - | 3,611 | - | 9,797 |
| Studies and contracting work | - | 2,018 | - | 5,235 |
| Total development costs | 127,216 | 67,890 | 285,002 | 181,009 |
| Other additions to property, plant and equipment | 2 | 32 | 642 | 967 |
| Total additions to property, plant and equipment for Platreef | 127,218 | 67,922 | 285,644 | 181,976 |
The company's total liabilities increased by $325 million to $2,226 million as at September 30, 2026, from $1,901 million as at December 31, 2025, with the increase mainly due to $207 million drawn down by Platreef under its senior debt facility, an increase in the deferred revenue associated with Platreef's streaming facilities of $55 million, an increase in the derivative liability associated with zinc and copper hedges of $20 million.
On January 23, 2025, the company issued debt securities with an aggregate principal of $750 million (the Senior Notes) and a maturity date of January 23, 2030. The Senior Notes carry a coupon of 7.875% per annum payable semi-annually in arrears on January 23 and July 23 each year, commencing on July 23, 2025.
LIQUIDITY AND CAPITAL RESOURCES
The company had $643 million in cash and cash equivalents as at September 30, 2026. At this date, the company had a consolidated working capital surplus of approximately $547 million, compared to $626 million as at December 31, 2025.
The company's capital expenditure guidance can be summarized as follows:
| Capital Expenditure | YTD 2026 Actuals (2) | 2026 Guidance | 2027 Guidance |
| ($' million) | ($' million) | ($' million) | |
| Kamoa-Kakula | |||
| Expansion capital (1) | 413 | 600 - 675 | 500 - 650 |
| Sustaining capital | 384 | 500 - 525 | 450 - 500 |
| 797 | 1,100 - 1,200 | 950 - 1,150 | |
| Platreef | |||
| Phase 2 capital | 275 | 415 - 445 | 455 - 495 |
| 275 | 415 - 445 | 455 - 495 | |
| Kipushi | |||
| Sustaining capital | 48 | 60 | 35 |
| 48 | 60 | 35 |
Figures in the above table are presented on a 100% basis.
(1) Expansion capital guidance at Kamoa-Kakula for 2026 and 2027 can be attributed 75% to accelerated mining development works, ventilation and dewatering infrastructure, and 25% to completion of smelter, power and Project 95 initiatives.
(2) Year-to-date capital expenditure excludes non-cash additions.
The capital expenditure guidance range for Kamoa-Kakula has been updated to reduce the upper end of the 2026 guidance by $200 million and to defer that and include it in the 2027 guidance range. The 2027 capital expenditure guidance excludes estimated capital expenditure for open pit mining at Kamoa estimated to be $100 million to $200 million.
The capital expenditure guidance range for Platreef has been updated to account for the weaker dollar, when compared to the South African Rand, as assumed in the Platreef Feasibility Study. The Feasibility Study assumed a USD:ZAR exchange rate of 18.00, with the guidance updated assuming an exchange rate of $16.50. This has a circa $75 million impact on 2026 and 2027, with the full impact added to the 2027 guidance. Additionally, the 2026 guidance has been increased by $65 million to account for additional costs capitalized due to the delay in reaching commercial production on the Phase 1 concentrator.
Ivanhoe's exploration budget for 2026 was set to approximately $127 million, with $86 million earmarked for exploration activities focused on the Western Forelands Project. A total of $75 million has been spent on exploration in the nine months ended September 30, 2026.
The cash flows by segment for the three and nine months ended September 30, 2026, and for the same period in 2025 is as follows:
| Three months ended | Nine months ended | |||
| September 30, | September 30, | |||
| 2026 | 2025 | 2026 | 2025 | |
| $'000 | $'000 | $'000 | $'000 | |
| Cash flows from operating activities | ||||
| Kamoa Holding joint venture | - | - | - | - |
| Kipushi properties | 60,625 | 992 | 154,563 | (11,387) |
| Platreef properties | 10,746 | (293) | (4,087) | (5,140) |
| Treasury | (35,094) | (7,894) | (87,451) | (12,238) |
| Other | (43,747) | (24,603) | (77,387) | (57,619) |
| Net cash used in operating activities | (7,470) | (31,798) | (14,362) | (86,384) |
| Cash flows from investing activities | ||||
| Kamoa Holding joint venture | - | (66,825) | (74,250) | (66,825) |
| Kipushi properties | (19,319) | (14,160) | (48,170) | (67,797) |
| Platreef properties | (125,382) | (65,124) | (277,960) | (172,903) |
| Treasury | (1) | (1,369) | 99,142 | 966 |
| Other | 1,814 | (2,720) | (7,070) | (6,358) |
| Net cash used in investing activities | (142,888) | (150,198) | (308,308) | (312,917) |
| Cash flows from financing activities | ||||
| Kamoa Holding joint venture | - | - | - | - |
| Kipushi properties | (13,954) | 12,000 | (53,721) | 22,900 |
| Platreef properties | 178,779 | - | 245,010 | 29,318 |
| Treasury | (819) | 543,685 | 1,979 | 1,274,044 |
| Other | 2,331 | 1,035 | (1,256) | (744) |
| Net cash generated from financing activities | 166,337 | 556,720 | 192,012 | 1,325,518 |
| Effect of foreign exchange rates on cash | (8,608) | 12,662 | (11,187) | 12,032 |
| Net cash (outflow) inflow by segment | ||||
| Kamoa Holding joint venture | - | (66,825) | (74,250) | (66,825) |
| Kipushi properties | 27,352 | (1,168) | 52,672 | (56,284) |
| Platreef properties | 64,143 | (65,417) | (37,037) | (148,725) |
| Treasury | (35,914) | 534,422 | 13,670 | 1,262,772 |
| Other | (39,602) | (26,288) | (85,713) | (64,721) |
| Effect of foreign exchange rates on cash | (8,608) | 12,662 | (11,187) | 12,032 |
| Net cash inflow (outflow) | 7,371 | 387,386 | (141,845) | 938,249 |
| Cash and cash equivalents - beginning of the period | 635,322 | 668,206 | 784,538 | 117,343 |
| Cash and cash equivalents - end of the period | 642,693 | 1,055,592 | 642,693 | 1,055,592 |
PRO-RATA FINANCIAL RATIOS
The following pro-rata financial ratios have been calculated by aggregating the contributions of the company with the contributions from the Kamoa-Kakula joint venture, pro-rata to the company's effective shareholding in the Kamoa-Kakula joint venture.
| (in millions of $, except ratios) | September 30, | December 31, |
| 2026 | 2025* | |
| Pro-rata total debt | 2,475.7 | 2,180.0 |
| Pro-rata cash and cash equivalents and short-term investment | 785.0 | 1,010.4 |
| Pro-rata net debt | 1,690.7 | 1,169.6 |
| Pro-rata net debt to Adjusted EBITDA (1) | 2.26x | 2.02x |
(1) Pro-rata net debt to Adjusted EBITDA ratio is a non-GAAP financial measure. Pro-rata net debt to Adjusted EBITDA ratio is pro-rata net debt divided by Adjusted EBITDA for the twelve months ended at the reporting period, expressed as the number of times Adjusted EBITDA needs to be earned to repay the pro-rata net debt.
The company's pro-rata total debt is summarized as follows:
| September 30, | December 31, | |
| 2026 | 2025* | |
| $'millions | $'millions | |
| Consolidated indebtedness of the company: | ||
| Senior notes | 747.4 | 759.2 |
| Senior debt facility | 279.7 | 96.4 |
| Advance payment facilities | 94.0 | 121.0 |
| Overdraft facilities | 33.7 | 80.5 |
| Other borrowings | 284.5 | 199.0 |
| 1,439.3 | 1,256.1 | |
| Pro-rata indebtedness of Kamoa Holding joint venture | ||
| Term loan facilities | 507.7 | 423.3 |
| Advance payment facilities | 356.9 | 359.1 |
| Provisional payment facilities | 31.4 | 32.0 |
| Overdraft facilities | 140.4 | 109.5 |
| 1,036.4 | 923.9 | |
| Pro-rata total debt | 2,475.7 | 2,180.0 |
The pro-rata cash and cash equivalents of the company are summarized as follows:
| September 30, | December 31, | |
| 2026 | 2025* | |
| $'millions | $'millions | |
| Consolidated cash and cash equivalents and short-term investment of the company | 642.7 | 885.2 |
| Pro-rata cash and cash equivalents of Kamoa Holding joint venture | 142.3 | 125.2 |
| Pro-rata cash and cash equivalents and short-term investment | 785.0 | 1,010.4 |
The pro-rata net debt of the company is summarized as follows:
| September 30, | December 31, | |
| 2026 | 2025* | |
| $'millions | $'millions | |
| Pro-rata total debt | 2,475.7 | 2,180.0 |
| Pro-rata cash and cash equivalents and short-term investment | 785.0 | 1,010.4 |
| Pro-rata net debt | 1,690.7 | 1,169.6 |
The Adjusted EBITDA of the company for the twelve months ended September 30, 2026 is summarized as follows:
| Twelve months | |||||
| ended | |||||
| September 30, 2026 | Q3 2026 | Q2 2026 | Q1 2026 | Q4 2025 | |
| $'millions | $'millions | $'millions | $'millions | $'millions | |
| Profit (loss) after taxes | 129.0 | 44.8 | 46.3 | (2.0) | 39.9 |
| Finance income | (180.7) | (46.7) | (45.0) | (43.9) | (45.1) |
| Current and deferred tax | 67.9 | 18.5 | 10.6 | 3.0 | 35.8 |
| Finance costs | 23.8 | 5.8 | 4.6 | 4.1 | 9.3 |
| Unrealized foreign exchange (gain) loss | (15.8) | 1.1 | (0.1) | 6.7 | (23.5) |
| Depreciation | 74.8 | 23.0 | 5.0 | 21.6 | 25.2 |
| Amortization of mineral property | 22.6 | 6.9 | 5.3 | 5.4 | 5.0 |
| EBITDA | 121.6 | 53.4 | 26.7 | (5.1) | 46.6 |
| Share of (profit) loss from joint venture net of tax | (45.2) | (25.3) | (16.3) | 42.0 | (45.6) |
| Company's share of EBITDA from Kamoa-Kakula joint venture (1) | 628.9 | 189.9 | 151.6 | 157.9 | 129.5 |
| Non-cash share-based payments | 17.6 | 5.7 | 4.1 | 3.5 | 4.3 |
| Loss (gain) on fair valuation of derivative liability | 30.6 | 17.6 | 17.2 | (7.3) | 3.1 |
| Modification gain on financial liability | (4.4) | - | (4.4) | - | - |
| Adjusted EBITDA | 749.1 | 241.3 | 178.9 | 191.0 | 137.9 |
(1) The company's attributable share of EBITDA from the Kamoa-Kakula joint venture is calculated using the company's effective shareholding in Kamoa Copper SA (39.6%), Ivanhoe Mines Energy DRC SARL (49.5%), Kamoa Holding Limited (49.5%), Kamoa Services (Pty) Ltd (49.5%) and the Kamoa Centre of Excellence (49.5%).
* The comparative information presented in the tables above, for the year ended December 31, 2025, has been restated, to include the company's overdraft facilities in the pro-rata total debt metric and the company's short-term investments in the pro-rata cash and cash equivalents and short-term investments metric. This restatement facilitates a more meaningful comparison with the pro-rata financial ratios as at September 30, 2026.
NON-GAAP FINANCIAL PERFORMANCE MEASURES
Cash cost (C1) per pound is a non-GAAP financial measure. These are disclosed to enable investors to better understand the performance of Kamoa-Kakula and Kipushi in comparison to other copper and zinc producers respectively who present results on a similar basis.
Cash cost (C1) is prepared on a basis consistent with the industry standard definitions by Wood Mackenzie cost guidelines but is not a measure recognized under IFRS Accounting Standards. In calculating the C1 cash cost for Kamoa-Kakula, the costs are measured on the same basis as the company's share of profit from the Kamoa Holding joint venture that is contained in the financial statements. C1 cash cost is used by management to evaluate operating performance and includes all direct mining, processing, and general and administrative costs. Smelter charges and freight deductions on sales to the final port of destination, which are recognized as a component of sales revenues, are added to C1 cash cost to arrive at an approximate cost of finished metal. C1 cash cost and C1 cash cost per pound exclude royalties, production taxes, and non-routine charges as they are not direct production costs.
Reconciliation of Kamoa-Kakula's cost of sales to C1 cash cost, including on a per pound basis:
| Three months ended | Nine months ended | |||
| September 30, | September 30, | |||
| 2026 | 2025 | 2026 | 2025 | |
| $'000 | $'000 | $'000 | $'000 | |
| Cost of sales | 678,297 | 438,230 | 1,907,062 | 1,531,687 |
| General and administrative expenditure | 60,045 | 57,490 | 153,849 | 131,241 |
| Logistics, treatment and refining charges | 29,457 | 50,681 | 88,441 | 262,909 |
| Depreciation | (182,264) | (113,987) | (506,641) | (358,996) |
| Sulphuric acid credits | (101,421) | - | (207,267) | - |
| Royalties and production taxes | (59,964) | (41,693) | (155,516) | (179,246) |
| Non-cash adjustments to inventory | 66,463 | 44,395 | 53,286 | 87,110 |
| Extraordinary taxes | (7,139) | (11,363) | (31,767) | (12,323) |
| Power rebate | (8,282) | (3,512) | (21,338) | (10,637) |
| General and administrative expenditures of other group entities | (55) | (7,000) | (330) | (11,690) |
| Costs classified as abnormal due to seismic activity | (10) | (9,533) | (10) | (99,597) |
| C1 cash costs | 475,127 | 403,708 | 1,279,769 | 1,340,458 |
| Cost of sales per pound of payable copper sold ($ per lb.) | 4.59 | 3.23 | 4.44 | 2.54 |
| Cash cost (C1) per payable pound of copper in saleable product produced ($ per lb.) | 3.00 | 2.62 | 2.80 | 1.97 |
| Payable copper produced in final saleable product (tonnes) | 71,792 | 69,682 | 207,187 | 308,285 |
Figures in the above table are for the Kamoa-Kakula joint venture on a 100% basis.
Reconciliation of Kipushi's cost of sales to C1 cash cost, including on a per-pound basis:
| Three months ended | Nine months ended | |||
| September 30, | September 30, | |||
| 2026 | 2025 | 2026 | 2025 | |
| $'000 | $'000 | $'000 | $'000 | |
| Cost of sales | 174,725 | 122,151 | 404,940 | 304,139 |
| Logistics and treatment charges | 22,602 | 13,759 | 50,556 | 36,397 |
| General and administrative expenditure | 339 | 374 | 1,337 | 808 |
| Royalties and production taxes | (28,496) | (12,330) | (61,398) | (32,984) |
| Depreciation and amortization | (28,962) | (18,470) | (64,295) | (47,565) |
| General and administrative expenditures of other group entities | (1,508) | (933) | (2,529) | (3,254) |
| C1 cash costs | 138,700 | 104,551 | 328,611 | 257,541 |
| Cost of sales per pound of payable zinc sold ($ per lb.) | 1.14 | 1.11 | 1.09 | 1.12 |
| C1 cash costs per pound of payable zinc sold ($ per lb.) | 0.91 | 0.95 | 0.89 | 0.95 |
| Payable zinc sold in concentrate (tonnes) | 69,384 | 49,744 | 167,748 | 123,200 |
EBITDA, Adjusted EBITDA and EBITDA margin
EBITDA and Adjusted EBITDA are non-GAAP financial measures. Ivanhoe believes that Kamoa-Kakula's EBITDA and Kipushi's EBITDA are valuable indicators of each mine's respective ability to generate liquidity by producing operating cash flow to fund their working capital needs, service debt obligations, fund capital expenditures, and distribute cash to its shareholders. EBITDA and Adjusted EBITDA are also frequently used by investors and analysts for valuation purposes. Kamoa-Kakula's EBITDA, Kipushi's EBITDA, and the EBITDA and Adjusted EBITDA for the company are intended to provide additional information to investors and analysts and do not have any standardized definition under IFRS Accounting Standards and should not be considered in isolation or as a substitute for measures of performance prepared per IFRS Accounting Standards. EBITDA and Adjusted EBITDA exclude the impact of cash cost of financing activities and taxes, and the effects of changes in operating working capital balances and impairments and therefore are not necessarily indicative of operating profit or cash flow from operations as determined under IFRS Accounting Standards. Other companies may calculate EBITDA and Adjusted EBITDA differently.
The EBITDA margin is an indicator of Kamoa-Kakula's and Kipushi's respective overall health and denotes their respective profitability, which is calculated by dividing EBITDA by revenue. The EBITDA margin is intended to provide additional information to investors and analysts, does not have any standardized definition under IFRS Accounting Standards, and should not be considered in isolation or as a substitute, for measures of performance prepared per IFRS Accounting Standards.
Reconciliation of (loss) profit after tax to Kamoa-Kakula's EBITDA:
| Three months ended | Nine months ended | |||
| September 30, | September 30, | |||
| 2026 | 2025 | 2026 | 2025 | |
| $'000 | $'000 | $'000 | $'000 | |
| Profit (loss) after taxes | 58,267 | 26,022 | (20,120) | 329,149 |
| Depreciation | 186,952 | 118,571 | 519,483 | 373,375 |
| Finance costs | 145,792 | 110,781 | 344,032 | 223,010 |
| Current and deferred tax expense | 81,612 | 7,821 | 349,271 | 189,070 |
| Modification loss on advance payment facilities | (123) | - | 21,548 | - |
| Other taxes | 7,139 | 11,363 | 31,767 | 12,323 |
| Finance income | (6,195) | (5,918) | (17,689) | (17,377) |
| Unrealized foreign exchange (gain) loss | 4,772 | (73,043) | 32,287 | (62,637) |
| Impairment (1) | - | - | - | 68,202 |
| EBITDA | 478,216 | 195,597 | 1,260,579 | 1,115,115 |
Figures in the above table are for the Kamoa-Kakula joint venture on a 100% basis.
Reconciliation of loss after tax to Kipushi's EBITDA:
| Three months ended | Nine months ended | |||
| September 30, | September 30, | |||
| 2026 | 2025 | 2026 | 2025 | |
| $'000 | $'000 | $'000 | $'000 | |
| Segmented profit (loss) after taxes | 47,183 | 7,580 | 90,571 | (3,634) |
| Depreciation and amortization | 28,962 | 18,470 | 64,295 | 47,565 |
| Finance costs | 7,770 | 8,465 | 21,303 | 22,932 |
| Current and deferred tax expense (recovery) | 24,391 | (1,987) | 37,134 | (14,152) |
| Finance income | (561) | (597) | (1,645) | (1,801) |
| Unrealized foreign exchange loss (gain) | 601 | (5,257) | 6,080 | (4,433) |
| EBITDA | 108,346 | 26,674 | 217,738 | 46,477 |
Reconciliation of profit after tax to Ivanhoe's EBITDA and adjusted EBITDA:
| Three months ended | Nine months ended | |||
| September 30, | September 30, | |||
| 2026 | 2025 | 2026 | 2025 | |
| $'000 | $'000 | |||
| Profit after taxes | 44,819 | 30,552 | 89,045 | 188,077 |
| Finance income | (46,739) | (43,855) | (135,624) | (129,061) |
| Depreciation | 22,974 | 14,711 | 49,586 | 37,921 |
| Amortization of mineral property | 6,929 | 4,096 | 17,586 | 11,635 |
| Current and deferred tax expense (recovery) | 18,530 | (2,489) | 32,077 | (13,671) |
| Finance costs | 5,832 | 20,920 | 14,596 | 33,705 |
| Unrealized foreign exchange loss (gain) | 1,040 | (6,664) | 7,515 | (5,339) |
| EBITDA | 53,385 | 17,271 | 74,781 | 123,267 |
| Share of (profit) loss from joint venture net of tax | (25,251) | (11,305) | 512 | (134,957) |
| Company's share of EBITDA from Kamoa-Kakula joint venture(1) | 189,867 | 76,337 | 499,356 | 439,087 |
| Non-cash share-based payments | 5,702 | 4,333 | 13,235 | 12,553 |
| Loss on fair valuation of derivative liability | 17,638 | - | 27,530 | - |
| Modification gain on financial liability | - | - | (4,410) | - |
| Adjusted EBITDA | 241,341 | 86,636 | 611,004 | 439,950 |
(1) The company's attributable share of adjusted EBITDA from the Kamoa-Kakula joint venture is calculated using the company's effective shareholding in Kamoa Copper SA (39.6%), Ivanhoe Mines Energy DRC SARL (49.5%), Kamoa Holding Limited (49.5%), Kamoa Services (Pty) Ltd (49.5%) and the Kamoa Centre of Excellence (49.5%).
Reconciliation of profit after tax to Ivanhoe's EBITDA and adjusted EBITDA on a segmented basis:
| Nine months ended | ||||||
| September 30, 2026 | ||||||
| Kamoa Holding | Kipushi | Platreef | Treasury | All other segments | Total | |
| $'000 | $'000 | $'000 | $'000 | $'000 | $'000 | |
| Segmented (loss) profit after taxes | 115,761 | 90,571 | 848 | (42,825) | (75,310) | 89,045 |
| Finance income | (116,273) | (1,645) | (3,061) | (14,431) | (214) | (135,624) |
| Current and deferred tax expense (recovery) | - | 37,134 | 763 | - | (5,820) | 32,077 |
| Finance costs | - | 21,303 | - | - | (6,707) | 14,596 |
| Unrealized foreign exchange loss (gain) | - | 6,080 | 129 | 1,785 | (479) | 7,515 |
| Depreciation | - | 46,709 | - | 835 | 2,042 | 49,586 |
| Amortization of mineral property | - | 17,586 | - | - | - | 17,586 |
| EBITDA | (512) | 217,738 | (1,321) | (54,636) | (86,488) | 74,781 |
| Share of loss (profit) from joint venture net of tax | 512 | - | - | - | - | 512 |
| Company's share of EBITDA from Kamoa-Kakula joint venture | 499,356 | - | - | - | - | 499,356 |
| Non-cash share based payments | - | - | 446 | 12,789 | - | 13,235 |
| Loss on fair valuation of derivative liability | - | - | - | 27,530 | - | 27,530 |
| Modification gain on financial liability | - | - | (4,410) | - | - | (4,410) |
| Adjusted EBITDA | 499,356 | 217,738 | (5,285) | (14,317) | (86,488) | 611,004 |
DISCLOSURE OF SCIENTIFIC AND TECHNICAL INFORMATION
Disclosures of a scientific or technical nature in respect of the Kamoa-Kakula Copper Complex, the Platreef Mine and the Kipushi Mine, in this release have been reviewed and approved by Simon Bottoms who is considered, by virtue of his education, experience and professional association, a Qualified Person under the terms of NI 43-101. Mr. Bottoms is not considered independent under NI 43-101 as he is Ivanhoe Mines’ Executive Vice President, Technical Services. Mr. Bottoms has verified the technical data disclosed in this release.
Disclosures of a scientific or technical nature regarding the Western Forelands Exploration Project, as well as the company’s other exploration projects, in this release have been reviewed and approved by Tim Williams, who is considered, by virtue of his education, experience and professional association, a Qualified Person under the terms of NI 43-101. Mr. Williams is not considered independent under NI 43-101 as he is the Vice President, Geosciences, at Ivanhoe Mines. Mr. Williams has verified the technical data regarding the Western Forelands Exploration Project disclosed in this release.
The scientific and technical information with respect to the Kamoa-Kakula Copper Complex, the Platreef Mine and the Kipushi Mine, contained in this release is derived from and based upon the following current NI 43-101-compliant technical reports, and is qualified by reference to such technical reports:
Technical Report dated March 31, 2026, titled "Kamoa-Kakula Mineral Reserve and Mineral Resource Technical Report" prepared by AMC Mining Consultants South Africa (Pty) Ltd and The MSA Group (Pty) Ltd, covering the company's Kamoa-Kakula Copper Complex ("Kamoa-Kakula MRE");
Technical Report dated February 15, 2025, titled "Platreef Integrated Development Plan 2025", prepared by OreWin Pty Ltd, The MSA Group (Pty) Ltd, SRK Consulting (South Africa) (Pty) Ltd, DRA Projects (Pty) Ltd and WSP Global Inc. covering the company's Platreef Mine (the "Platreef IDP 2025"); and
Technical Report dated February 14, 2022, titled "Kipushi 2022 Feasibility Study" prepared by OreWin Pty Ltd, The MSA Group (Pty) Ltd, SRK Consulting (South Africa) (Pty) Ltd and METC Engineering covering the company's Kipushi Mine (the "Kipushi 2022 FS").
The Kamoa-Kakula MRE, the Platreef IDP 2025 and Kipushi 2022 FS, are collectively referred to as the "Technical Reports".
The technical information in this release has been updated with current information where applicable. Copies of the Technical Reports have been filed with Canadian securities regulatory authorities pursuant to NI 43-101 and are available for review under the company’s SEDAR+ profile at www.sedarplus.ca.
These technical reports include relevant information regarding the effective dates and the assumptions, parameters and methods of the mineral resource estimates on the Platreef Mine, the Kipushi Mine and the Kamoa-Kakula Copper Complex cited in this release, as well as information regarding data verification, exploration procedures and other matters relevant to the scientific and technical disclosure contained in this release in respect of the Platreef Mine, Kipushi Mine and Kamoa-Kakula Copper Complex.
Information contact
Follow Robert Friedland (@robert_ivanhoe) and Ivanhoe Mines (@IvanhoeMines_) on X.
Investors
Tommy Horton: +44 7866 913 207 (London)
Eric Zurmuehle: +1 203 451 5834 (New York)
Media
Tanya Todd: +1 604 331 9834 (Vancouver)
Website
www.ivanhoemines.com
FORWARD-LOOKING STATEMENTS
Certain statements in this news release constitute "forward-looking statements" or "forward-looking information" within the meaning of applicable securities laws. Such statements and information involve known and unknown risks, uncertainties, and other factors that may cause the actual results, performance, or achievements of the company, its projects, or industry results, to be materially different from any future results, performance, or achievements expressed or implied by such forward-looking statements or information. Such statements can be identified using words such as "may", "would", "could", "will", "intend", "expect", "believe", "plan", "anticipate", "estimate", "scheduled", "forecast", "predict" and other similar terminology, or state that certain actions, events, or results "may", "could", "would", "might" or "will" be taken, occur or be achieved. These statements reflect the company's current expectations regarding future events, performance, and results and speak only as of the date of this release.
Such statements include, without limitation: (i) statements that cash costs are expected to trend lower than $2.50 per pound prior to the Phase 4 expansion, (ii) statements that sulphuric acid prices are expected to remain elevated for the foreseeable future, (iii) statements that Kamoa-Kakula full-year production expected to be approximately 290,000 tonnes of copper in saleable products; (iv) statements regarding Kamoa-Kakula's 2027 production guidance of 300,000 - 350,000 tonnes of copper and steady-state capacity, using the existing Phase 1, 2 & 3 concentrators, reducing to 400,000 - 450,000 tonnes of copper; (v) statements that pre-stripping of first starter pits to start in Q1 2027, with first ore expected in Q3 2027; (vi) statements that Phase 4 expansion to upgrade production capacity of Kamoa-Kakula to approximately 500,000 tonnes per annum, that the timeline to deliver Phase 4 expansion from approval is 18-24-month and that detailed engineering design for the Phase 4 expansion is expected to commence in Q1 2027; (vii) statements that the Kamoa-Kakula's on-site hybrid solar photovoltaic facility with battery energy storage system is expected to significantly reduce the diesel used by on-site backup generators; (viii) statements with respect to the company's 2026 production guidance for the Kipushi Mine being 270,000 to 290,000 (previously 240,000 to 290,000) tonnes of zinc in concentrate, which is expected to make Kipushi one of the top three zinc mines in the world; (ix) statements that the Kipushi hybrid solar PV facility is expected to be operational by mid 2028; (x) statements that Phase 2 operations at Platreef are expected to have a design capacity of over 450,000 ounces of platinum, palladium, rhodium, and gold (3PE + Au), plus approximately 9,000 tonnes of nickel and 6,000 tonnes of copper; (xi) statements that Shaft #2 is expected to be ready to hoist labour and materials by the end of 2028 and ore by the end of 2029; (xii) statements that year-end copper inventories at Kamoa-Kakula are expected to be between 35,000 and 40,000 tonnes; (xiii) statements with respect to C1 cash cost guidance for Kamoa-Kakula of $2.50 to $3.00 per payable pound; (xiv) statements that the Kamoa-Kakula Copper Complex is expected to include mining from open pits to support underground operations, that pre-stripping of Kamoa open pits is expected to commence in Q1 2027, that by the end of 2028, approximately 3.5 million tonnes of ore at an average grade of 2.5% is expected to have been mined from the open pits and that pre-stripping of two additional starter pits at Kamoa will start by the end of 2028; (xv) statements that the Phase 4 expansion is expected to have a capital intensity of approximately $9,000-$12,000 per tonne of annualized copper production, including development of the supporting open pit operations, and is expected to sustain Kamoa-Kakula's copper production at approximately 500,000 tonnes per annum; (xvi) statements with respect to the company's capital expenditures guidance for 2026 and 2027; (xvii) statements that the Solar PV facility at Kamoa-Kakula will be designed to provide 10 MW of continuous baseload power, providing approximately 50% of the Kipushi Mines' energy requirements and that the facility is expected to be commissioned and operational in Q2 2028; (xviii) statements that in the fourth quarter, Kipushi Corporation is expected to upstream excess cash from the DRC subsidiary to Ivanhoe Mines; (xix) statements with respect to Kipushi's 2026 guidance of 270,000 to 290,000 tonnes of zinc; (xx) statements that the Phase 2 expansion at Platreef is expected to complete in Q4 2027 and fully ramp up in Q4 2028; (xxi) statements that the stoping of higher-grade stopes is also expected to ramp up in Q4 2026 at Platreef; and (xxii) statements that shaft equipping is expected to commence in Q1 2028, shaft #2 is expected to be ready to hoist labour and materials by the end of 2028 and ready to hoist ore by the end of 2029, supporting both the steady-state operations of Phase 2, as well as the future Phase 3 expansion.
Also, all of the results of the Kamoa-Kakula MRE, the Platreef IDP 2025 feasibility study and the Kipushi 2022 feasibility study constitute forward-looking statements or information and include future estimates of internal rates of return, net present value, future production, estimates of cash cost, proposed mining plans and methods, mine life estimates, cash flow forecasts, metal recoveries, estimates of capital and operating costs and the size and timing of phased development of the projects.
Furthermore, concerning this specific forward-looking information concerning the operation and development of the Kamoa-Kakula Copper Complex, Platreef Project and Kipushi Mine, and the exploration of the Western Forelands Exploration Project, the Mokopane Feeder Exploration Project and the Chu-Sarya Basin Exploration JV, the company has based its assumptions and analysis on certain factors that are inherently uncertain. Uncertainties include: (i) the adequacy of infrastructure; (ii) geological characteristics; (iii) metallurgical characteristics of the mineralization; (iv) the ability to develop adequate processing capacity; (v) the price of copper, nickel, zinc, platinum, palladium, rhodium and gold; (vi) the availability of equipment and facilities necessary to complete development and exploration; (vii) the cost of consumables and mining and processing equipment; (viii) unforeseen technological and engineering problems; (ix) accidents or acts of sabotage or terrorism; (x) currency fluctuations; (xi) changes in regulations; (xii) the compliance by joint venture partners with terms of agreements; (xiii) the availability and productivity of skilled labour; (xiv) the regulation of the mining industry by various governmental agencies; (xv) the ability to raise sufficient capital to develop such projects; (xvi) changes in project scope or design; (xvii) recoveries, mining rates and grade; (xviii) political factors; (xviii) water inflow into the mine and its potential effect on mining operations; and (xix) the consistency and availability of electric power.
Forward-looking statements and information involve significant risks and uncertainties, should not be read as guarantees of future performance or results, and will not necessarily be accurate indicators of whether such results will be achieved. Many factors could cause actual results to differ materially from the results discussed in the forward-looking statements or information, including, however not limited to, the factors discussed above and under the "Risk Factors" heading in the company's MD&A for the three- and nine-months ended September 30, 2026, in the company's current annual information form, and elsewhere in this release, as well as unexpected changes in laws, rules or regulations, or their enforcement by applicable authorities; the failure of parties to contracts with the company to perform as agreed; social or labour unrest; changes in commodity prices; and the failure of exploration programs or studies to deliver anticipated results or results that would justify and support continued exploration, studies, development or operations.
Although the forward-looking statements contained in this release are based upon what management of the company believes are reasonable assumptions, the company cannot assure investors that actual results will be consistent with these forward-looking statements. These forward-looking statements are made as of the date of this release and are expressly qualified in their entirety by this cautionary statement. Subject to applicable securities laws, the company does not assume any obligation to update or revise the forward-looking statements contained herein to reflect events or circumstances occurring after the date of this release.
The company's actual results could differ materially from those anticipated in these forward-looking statements as a result of the factors outlined in the "Risk Factors" section in the company's MD&A for the three- and nine-months ended September 30, 2026, in the company's current annual information and elsewhere in this release.
ADDITIONAL INFORMATION
Additional information regarding the company, including the company's Annual Information Form, is available on SEDAR+ at www.sedarplus.ca.
To view the source version of this press release, please visit https://www.newsfilecorp.com/release/322386
Source: Ivanhoe Mines Ltd.